Spain and United Kingdom Expand Tourist Taxes for 2027: New Hotel and Holiday Rental Levies Hit Catalonia, Cardiff, and Scotland
Spain and the UK are introducing higher tourist taxes in 2027 across Catalonia, the Basque Country, Barcelona, Cardiff, and Scotland, impacting hotels and holiday rentals.
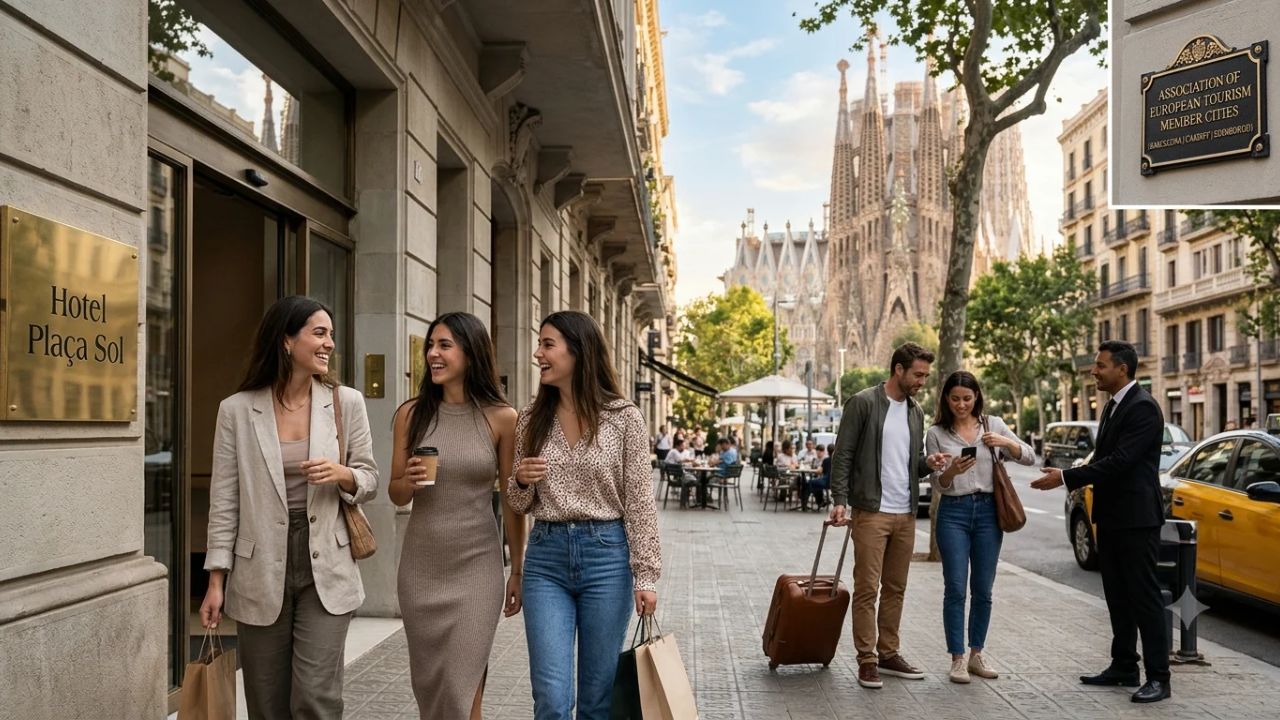
Image generated by AI
Travelers planning European vacations will face significantly higher accommodation costs in 2027 as regional governments across Spain and the United Kingdom implement sweeping new tourist taxes and steep municipal surcharges. From new hotel tier levies in the Basque Country and rate hikes across Catalonia and Barcelona to fixed nightly charges in Cardiff and percentage-based visitor taxes across Scotland, overnight visitors must adjust their travel budgets to account for local taxation rules.
Rather than operating uniform nationwide systems, Spain and the United Kingdom are allowing autonomous communities, devolved nations, and individual municipal councils to establish targeted accommodation charges. The resulting revenue streams are designated to fund civic public services, maintain cultural heritage monuments, and mitigate the environmental pressures generated by mass tourism. However, because tax calculation methods vary widely—spanning fixed per-person rates, hotel star-rating scales, and percentage levies applied to pre-tax room bills—travelers must pay closer attention to how these charges are billed.
Spain's Expanding Tourist Tax Network: Basque Country Rollout and Catalan Surcharges
Spain's tourist tax architecture has expanded progressively from initial adoption in Catalonia and the Balearic Islands to Galician destinations including Vigo, A Coruña, and Santiago de Compostela. Starting in 2027, this framework incorporates new regions while raising existing municipal ceilings.
1. Basque Country: Category-Based Taxation Effective January 1, 2027
Beginning January 1, 2027, the Basque Country (Euskadi) introduces a comprehensive visitor levy covering rural lodges, traditional hotels, guesthouses, vacation rentals, campsites, and cruise ships. The tax structure scales according to accommodation classification:
| Accommodation Category | Base Tourist Tax Per Night |
|---|---|
| Rural Accommodation & Agritourism | €0.50 – €1.26 |
| One-Star Hotels, Guesthouses, Hostels & Campsites | €0.75 – €1.50 |
| Two-Star Hotels | €1.00 – €2.00 |
| Three-Star Hotels & Tourist Apartments | €1.50 – €3.00 |
| Four-Star Hotels | €2.00 – €4.00 |
| Five-Star Hotels & Cruise Ship Stays | €2.50 – €5.00 |
To provide localized flexibility, Basque municipalities containing more than 750 licensed accommodation beds are legally authorized to apply an additional municipal surcharge of up to 50% on top of the base regional rate. In high-density travel centers where councils apply the maximum surcharge, the nightly fee for a five-star hotel can reach €7.50 per night. Conversely, smaller rural communities possessing 25 accommodation places or fewer hold the statutory authority to waive the tax entirely, creating noticeable price differences between neighboring towns.
2. Catalonia: Regional Rate Increases Taking Effect April 2027
Catalonia is revising its existing tourist tax schedule upwards starting April 2027, placing heavier financial contributions on upper-tier hospitality properties:
- Five-Star Hotels, Luxury Resorts & Luxury Campsites: €6.00 per person, per night.
- Tourist Apartments and Short-Term Holiday Rentals: €2.50 per person, per night.
- Four-Star Hotels and Superior Establishments: €2.40 per person, per night.
- Standard Campsites and Rural Lodges: €1.20 per person, per night.
- Youth Hostels and Budget Refuges: €1.00 per person, per night.
- Cruise Ship Passengers: €4.00 to €6.00 per night, depending on port-of-call transit duration.
In addition to regional adjustments, several prominent Catalan municipalities have enacted supplementary local surcharges, including Castelldefels, Esplugues, l’Hospitalet de Llobregat, El Prat de Llobregat, Sabadell, Sant Cugat del Vallès, and Sant Just Desvern.
3. Barcelona: Escalating Municipal Surcharges for 2027 and 2028
Visitors staying within Barcelona face a dual-layered taxation mechanism comprising both the regional Catalan base tax and the independent Barcelona municipal surcharge.
While the city's base tax remains between €1.00 and €7.00 depending on hotel grading, the municipal surcharge increases as follows:
- April 2027: The municipal surcharge climbs from €5.00 to €6.00 per person, per night.
- April 2028: The surcharge rises again to €7.00 per person, per night.
Because the municipal surcharge applies on top of the regional base rate rather than replacing it, guests booking upscale or five-star rooms in Barcelona from April 2027 will pay combined accommodation taxes reaching €12.00 to €13.00 per person, per night, making the city one of the highest-taxed urban tourist destinations in Southern Europe.
United Kingdom Visitor Levies: Cardiff's Fixed Rates and Scotland's Percentage System
In the United Kingdom, tourist taxation is taking shape through distinct regional frameworks, with Wales opting for flat per-person rates and Scotland enacting percentage-based models.
Cardiff: Fixed Nightly Accommodation Levy Effective April 1, 2027
The Welsh capital will inaugurate a visitor accommodation levy on April 1, 2027. The tax applies to commercial overnight lodging, including hotels, bed-and-breakfasts, holiday cottages, and short-term self-catering rentals:
| Accommodation Type | Nightly Rate (Excluding VAT) | Nightly Rate (Including 20% VAT) |
|---|---|---|
| Hotels, Guesthouses, Cottages & Self-Catering Rentals | £1.30 per person | £1.56 per person |
| Campsite Pitches, Hostels & Student Accommodations | £0.75 per person | £0.90 per person |
Because the levy is subject to standard UK Value Added Tax (VAT) when collected by VAT-registered lodging providers, hospitality businesses will charge guests the higher VAT-inclusive rate. For example, a couple spending five nights in a central Cardiff hotel will incur an additional £15.60 in accommodation tax on their final checkout statement.
Scotland: Percentage-Based Visitor Levies Across Four Local Authorities
Under powers granted by the Scottish Parliament, municipal councils across Scotland are implementing visitor levies calculated as a direct percentage of eligible accommodation costs. Unlike flat fees, these charges fluctuate with the nightly room rate:
| Scottish Authority | Scheduled Effective Date | Approved Visitor Levy Rate | Tax Application Scope |
|---|---|---|---|
| Glasgow | January 2027 | 5% | Pre-VAT room rate on eligible overnight stays |
| Aberdeen | April 2027 | 7% | Pre-VAT room rate across hotels & holiday rentals |
| Stirling | June 2027 | 3% | Pre-VAT room rate in historic city & rural bounds |
| West Dunbartonshire | July 2027 | 5% | Pre-VAT room rate around Loch Lomond corridor |
The Scottish levies are calculated exclusively on eligible room accommodation costs prior to the application of 20% VAT. Ancilary guest expenditures—such as parking, restaurant meals, bar tabs, and sightseeing transport—are explicitly excluded from the tax base. For example, a traveler booking a four-night hotel stay in Aberdeen priced at £500 before VAT will pay an additional £35 (7% of £500) in visitor levy.
Comparative Overview: Tourist Tax Structures in Spain and the United Kingdom (2027)
The table below contrasts the legal frameworks, collection mechanisms, and cost implications across newly taxing jurisdictions in Spain and the UK:
| Jurisdiction | Implementation Date | Tax Calculation Model | Typical Nightly Cost Range | Key Municipal Surcharges or Rules |
|---|---|---|---|---|
| Basque Country (Spain) | January 1, 2027 | Star-rating tiers per night | €0.50 – €5.00 | Up to 50% municipal surcharge in towns with >750 beds (max €7.50); waived in towns with ≤25 beds |
| Catalonia (Spain) | April 2027 | Property classification tiers | €1.00 – €6.00 | Higher rates on 5-star hotels (€6) and vacation rentals (€2.50); municipal additions in suburban towns |
| Barcelona (Spain) | April 2027 / April 2028 | Regional tier + municipal surcharge | €6.00 – €13.00 combined | Municipal surcharge increases to €6 in April 2027 and €7 in April 2028 on top of base rates |
| Cardiff (Wales, UK) | April 1, 2027 | Fixed flat fee per person | £0.75 – £1.30 (+20% VAT = £0.90 – £1.56) | Uniform flat fee; campsite and hostel stays receive discounted rates |
| Glasgow (Scotland, UK) | January 2027 | Percentage of room rate | 5% of pre-VAT lodging total | Calculated strictly on accommodation charge, excluding food and beverages |
| Aberdeen (Scotland, UK) | April 2027 | Percentage of room rate | 7% of pre-VAT lodging total | Highest approved percentage levy in Scotland; applied to business and leisure guests |
| Stirling (Scotland, UK) | June 2027 | Percentage of room rate | 3% of pre-VAT lodging total | Covers central heritage hub, Trossachs gateway, and regional guesthouses |
| West Dunbartonshire (UK) | July 2027 | Percentage of room rate | 5% of pre-VAT lodging total | Targets accommodation providers along southern Loch Lomond travel corridors |
Budgeting Implications: How Tourist Taxes Alter Holiday Expenses
The expansion of accommodation levies shifts holiday budgeting from simple room comparisons to multi-variable expense modeling. Travelers must consider several practical financial realities when planning European itineraries in 2027:
1. Cumulative Family and Group Costs
Because taxes in the Basque Country, Catalonia, Barcelona, and Cardiff are assessed per person per night, costs multiply rapidly for families and travel groups. A family of four staying seven nights in a four-star hotel in Catalonia would pay: $$\text{4 guests} \times \text{7 nights} \times €2.40 = €67.20$$ In central Barcelona, that same family staying in a four-star property (base tax of €2.40 plus the €6.00 municipal surcharge) would incur: $$\text{4 guests} \times \text{7 nights} \times €8.40 = €235.20$$ This substantial additional outlay must be accounted for outside the baseline room price.
2. Disconnect Between Advertised OTA Rates and Local Check-in Payments
Online Travel Agencies (OTAs) such as Booking.com, Expedia, and Airbnb do not always incorporate local tourist taxes into their headline advertised prices. In many Spanish municipalities, local legislation mandates that visitor taxes be collected directly by the hotel front desk upon check-in or checkout, payable by credit card or cash. Travelers failing to read the fine print in booking confirmations may encounter unexpected checkout charges.
3. Cross-Border Regional Price Arbitrage
The variation in local tax powers creates opportunities for strategic itinerary planning. In the Basque Country, staying in smaller rural villages with 25 beds or fewer can eliminate the levy entirely compared to neighboring resort hubs where 50% surcharges apply. Similarly, visitors exploring central Scotland can base themselves in Stirling (3% levy) rather than Aberdeen (7%) or Glasgow (5%) to minimize lodging taxes on extended stays.
Traveler Logistics Guide: Navigating Tourist Taxes, Invoicing, and Rebooking in 2027
To manage the financial and operational impact of new European tourist taxes, travelers should follow these verified booking guidelines:
- Review Checkout Tax Breakdowns: When reserving lodging through third-party platforms, examine the "Taxes and Fees" line item before finalizing payment. Confirm whether local tourist levies are included in the prepaid total or flagged as "Payable at property."
- Request Itemized Hotel Invoices for Business Expense Reclaims: Corporate travelers visiting Glasgow, Aberdeen, or Barcelona should ensure their checkout receipts explicitly separate the accommodation fee, VAT, and local visitor levy. Under UK and Spanish tax regulations, visitor taxes are treated differently for corporate expense accounting and VAT reclamation.
- Factor VAT Rules into UK Holiday Calculations: In Cardiff, confirm whether the quoted room rate includes the 20% VAT applied to the visitor levy (£1.56 total for standard hotels). In Scotland, verify that percentage levies are applied strictly to the pre-VAT room cost rather than the gross amount.
- Inquire About Length-of-Stay Caps: Several European jurisdictions impose a statutory cap on tourist taxes, commonly exempting stays extending beyond 7 consecutive nights in a single property. If planning an extended sabbatical or digital nomad stay, verify with the property manager whether tax charges cease after day seven.
- Verify Youth and School Group Exemptions: In Catalonia and the Basque Country, children under the age of 16 or 17 are frequently exempt from overnight tourist levies upon presentation of valid government identification. Ensure family bookings reflect these legal exemptions.
Strategic Outlook: Funding Civic Resilience and Destination Stewardship
The expansion of accommodation levies across Spain and the United Kingdom reflects an evolving consensus in European destination management. Municipalities are moving away from unmanaged tourism growth toward models that require visitors to contribute directly to civic infrastructure.
Revenues generated by these 2027 taxes are legally earmarked to upgrade water treatment plants, expand municipal waste collection in historic quarters, subsidize public transport networks, and restore historic cultural landmarks. While travelers will navigate higher nightly expenses, transparent taxation structures help ensure that Europe's premier destinations remain ecologically sustainable, socially balanced, and culturally preserved for future generations.
FAQ: Spain and UK Tourist Tax Increases 2027
When does the Basque Country tourist tax take effect?
The Basque Country tourist tax begins on January 1, 2027, with tiered nightly rates ranging from €0.50 for rural stays to €5.00 for five-star hotels and cruise ships.
How high will Barcelona's total tourist tax be in 2027?
In April 2027, Barcelona's municipal surcharge increases to €6.00 per person per night. Combined with the regional Catalan base tax (€1.00 to €7.00), total nightly taxes will range from €7.00 to €13.00 depending on hotel category.
How is Cardiff's new tourist tax calculated?
Starting April 1, 2027, Cardiff charges a flat £1.30 per person per night (£1.56 including 20% VAT) for hotels and vacation rentals, and £0.75 per person (£0.90 with VAT) for hostels and campsites.
Which Scottish cities are introducing visitor levies in 2027?
Glasgow introduces a 5% levy in January 2027, Aberdeen introduces a 7% levy in April 2027, Stirling implements a 3% levy in June 2027, and West Dunbartonshire adds a 5% levy in July 2027.
Related Travel Guides
South American City-Break Travel Costs: Buenos Aires Sets the Pace for Santiago and Bogotá in 2026
Spain Implements 10 Percent VAT on Short-Stay Holiday Rentals Across Major Tourist Hubs
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Naina Thakur
Contributor & Travel Specialist
Travel enthusiast and legal writer covering visa regulations, responsible tourism, and cultural journeys across global destinations.
Learn more about our team →