Southeast Asian Airports Face US$341 Billion Capital Deficit as Travel Demand Outpaces Runway Capacity
ASEAN airport networks require US$341 billion in capital investments through 2056, including US$108 billion by 2036, according to ACI Asia-Pacific and Middle East data.
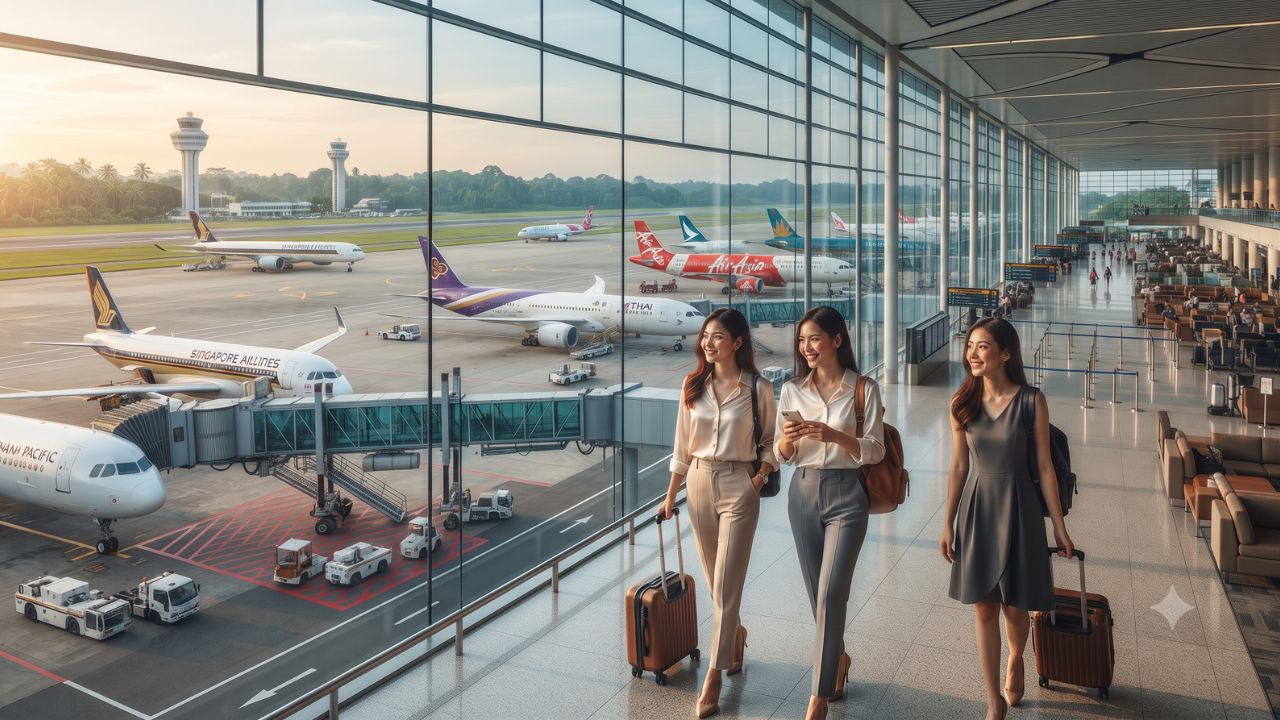
A capital requirement of US$341 billion across Southeast Asian airport infrastructure through 2056—frontloaded by an immediate US$108 billion needed before 2036—threatens to constrain regional connectivity as passenger traffic surges beyond physical terminal capacity. The assessment, published on 7 October 2026 by Airports Council International (ACI) Asia-Pacific & Middle East, underscores an intensifying structural bottleneck across the 10 member states of the Association of Southeast Asian Nations. With international air arrivals in ASEAN reaching 84.8 million travelers in 2025 and generating approximately US$127 billion in tourism spending, the operational gap between bilateral open-skies policies and actual runway, gate, and tarmac capacity is rapidly widening.
While air transport and airport infrastructure currently anchor US$244 billion in economic output and sustain 23.3 million jobs across the bloc, long-term projections indicate that unconstrained aviation liberalisation could unlock an additional 450,000 employment positions and US$4.3 billion in annual gross domestic product. However, translating regulatory ambition into passenger throughput requires massive capital procurement. Without firm public-private financing frameworks and accelerated runway delivery, rising passenger volumes will inevitably lead to severe air traffic delays, restricted airline scheduling, and elevated ticket prices across primary leisure and business gateways.
The Structural Divide Between Traffic Growth and Terminal Funding
The capital test facing ASEAN civil aviation unfolds across two distinct planning horizons. The initial phase running through 2036 demands US$108 billion to modernize saturated primary hubs, extend runways for widebody long-haul operations, and automate terminal processing. The subsequent twenty-year horizon from 2037 through 2056 calls for an additional US$233 billion to develop secondary regional aerodromes, construct decentralized high-speed transit links, and replace aging domestic airside assets.
| Investment Planning Horizon | Capital Requirement (USD) | Primary Strategic Focus | Key Operational Milestones |
|---|---|---|---|
| Phase I: Near-Term (Through 2036) | US$108 Billion | Primary hub debottlenecking, digital passenger flow, runway expansion | Upgrading mega-gateways, air traffic management modernization |
| Phase II: Long-Term (2037–2056) | US$233 Billion | Secondary island airports, greenfield hubs, regional multi-modal transit | Decentralized domestic networks, net-zero carbon infrastructure |
| Total Cumulative Capex Requirement | US$341 Billion | Pan-ASEAN single aviation network integration | Complete regional infrastructure alignment by 2056 |
| 2025 International Air Arrivals Baseline | 84.8 Million Passengers | Core leisure and corporate tourism inflow | Inbound foreign visitor arrivals across 10 member states |
| 2025 Direct Tourism Spending | US$127 Billion | Direct hospitality and service economy contribution | Dispersed spending across retail, transport, and lodging |
| Unconstrained Liberalisation Upside | +450,000 Jobs / +US$4.3B GDP | High-connectivity economic multiplier | Contingent upon full runway and terminal delivery |
| Current Economic Footprint Baseline | US$244B GDP / 23.3M Jobs | Existing civil aviation baseline across ASEAN | Foundation of current regional commercial transport |
These figures quantify capital expenditure requirements rather than committed treasury allocations or approved sovereign debt facilities. For airline network planners and commercial operators, this distinction is critical. Multi-billion-dollar infrastructure estimates signal the magnitude of regional demand, but until individual civil aviation authorities finalize project finance structures, statutory procurement contracts, and ground-breaking timelines, available airline capacity remains strictly capped by legacy tarmac configurations.
Regulatory Alignment Under the ASEAN Single Aviation Market
The infrastructure funding deficit intersects directly with regional regulatory reforms led by the Association of Southeast Asian Nations (ASEAN). Over the past decade, member governments established frameworks for the ASEAN Single Aviation Market (ASAM) alongside multilateral agreements governing scheduled passenger air services and air freight carriage. Concurrently, the ASEAN Tourism Agreement formally established policy mandates to market the trade bloc as a unified travel destination by harmonizing aviation standards and liberalizing cross-border traffic rights.
However, a fundamental disconnect exists between regulatory traffic rights and physical airport capacity. An open-skies treaty allows designated airlines to schedule new frequencies between capital cities, but it cannot manufacture vacant landing slots, construct aircraft parking stands, or alleviate baggage handling saturation. When aerodrome infrastructure fails to keep pace with liberalized commercial route permissions, the result is chronic runway holding patterns, extended gate delays, and artificial caps on flight growth.
Furthermore, international travelers frequently conflate regional aviation pacts with simplified immigration policies. While the ASEAN Single Aviation Market liberalizes airline market access, it confers zero uniform immigration or visa privileges. Travelers moving across Southeast Asia remain subject to individual national visa regimes, electronic travel authorizations, and bilateral border clearance protocols.
Expert Analysis: Slot Scarcity, Airfare Pricing, and the Regional Tourism Economy
For travelers booking flights into and across Southeast Asia, the direct consequence of infrastructure underfunding is structural fare inflation and schedule rigidity. When passenger demand grows at double-digit rates while runway slots at key gateways remain fixed, basic market economics dictates that airlines optimize yields by raising baseline ticket prices. Instead of passing on the cost efficiencies of new-generation aircraft, operators face rising airport landing tariffs and passenger service charges levied by terminal authorities attempting to finance capital projects.
According to operational analysis benchmarks maintained by the International Air Transport Association (IATA), airport infrastructure must expand ahead of demand curves to prevent severe airline operating inefficiencies. In Southeast Asia, where secondary ground transport and high-speed rail networks remain fragmented outside major metropolitan zones, air travel functions as the indispensable connective tissue for trade and tourism. When international air arrivals generated US$127 billion in 2025 across ASEAN, that capital flowed directly through terminal gates into regional hotels, dining establishments, and transport operators.
If the US$108 billion near-term capital expenditure fails to materialize by 2036, secondary tourism destinations that rely on feeder flights from primary hubs will bear the economic brunt. Congested capital gateways will naturally prioritize lucrative long-haul international flights over thin domestic feeder routes, severing regional travel itineraries and concentrating economic benefits within saturated urban centers.
Key Takeaways
- Massive Capital Deficit: ASEAN airports require US$341 billion in capital investments through 2056, divided into US$108 billion through 2036 and US$233 billion from 2037 to 2056.
- Economic Scale: Regional air connectivity currently sustains US$244 billion in GDP and 23.3 million jobs, with international tourists contributing US$127 billion across 84.8 million air arrivals in 2025.
- Unconstrained Growth Potential: Full aviation liberalisation backed by adequate runway and terminal capacity could unlock almost 450,000 additional jobs and US$4.3 billion in incremental GDP.
- Regulatory Asymmetry: Liberalization under the ASEAN Single Aviation Market grants route rights but cannot resolve physical slot bottlenecks, baggage handling limits, or runway shortages.
- Traveler Action: Passengers should evaluate published flight schedules and airport connection windows conservatively, recognizing that long-term regional investment plans do not ensure immediate capacity relief.
FAQ: Southeast Asian Airport Infrastructure 2026
What is the total projected investment needed for ASEAN airports?
According to ACI Asia-Pacific & Middle East, ASEAN airport infrastructure requires US$341 billion in total investment through 2056, including US$108 billion through 2036.
How many international tourists traveled to ASEAN by air in 2025?
Approximately 84.8 million international visitors arrived by air across ASEAN nations in 2025, generating roughly US$127 billion in tourism expenditure.
Does the ASEAN Single Aviation Market eliminate visa requirements?
No. Aviation liberalization agreements govern airline route rights and flight frequencies. National immigration and visa requirements remain entirely separate sovereign regulations.
Will projected airport expansions immediately lower airfares?
No. The figures represent capital requirements rather than funded projects. Ticket prices will remain governed by fuel costs, airline capacity constraints, and peak holiday travel demand.
Air transport liberalization cannot deliver on its economic promises until concrete runway construction catches up with regional treaty signatures.
Related Travel Guides
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Kunal K Choudhary
Co-Founder & Contributor
A passionate traveller and tech enthusiast. Kunal contributes to the vision and growth of Nomad Lawyer, bringing fresh perspectives and driving the community forward.
Learn more about our team →