US Inbound Tourism Squeezed: Overseas Arrivals Slump 11.8% as Local Spending Drops 9% Across Major Hubs
An 11.8% contraction in overseas visitor arrivals drove a sharp 9% drop in domestic destination expenditure down to $10.8 billion in August 2026, severely straining municipal tourism budgets from Las Vegas to Miami. According to data released by the National Travel and Tourism Office (NTTO), total international visitor spending across the United States slipped nearly 5% year on year to $19.9 billion. While headline exports experienced multi-billion-dollar contractions, the localized economic squeeze on hotels, restaurants, local transit, and retail revealed a structural crisis: high-spending, long-stay international travelers are retreating from American gateways, leaving tourism infrastructure built for continuous post-pandemic growth exposed to sudden oversupply.
Simultaneously, American residents traveled abroad in record numbers, spending $19.7 billion overseas in August—a 0.5% increase year on year. When weighed against the $19.9 billion in foreign receipts, the monthly U.S. travel trade surplus collapsed to an unprecedented low of just $157 million. While year-to-date travel receipts reached $165 billion through August (down nearly 1% compared to 2025) and maintained a cumulative surplus of almost $5.6 billion, the narrowing monthly margin indicates that the nation’s traditional tourism surplus is dangerously close to slipping into a deficit.
The Geography of Contraction: Where the International Drop Hits Hardest
The contraction in international travel is not uniform; it concentrates heavily on primary gateways, entertainment hubs, and border regions historically reliant on foreign visitors:
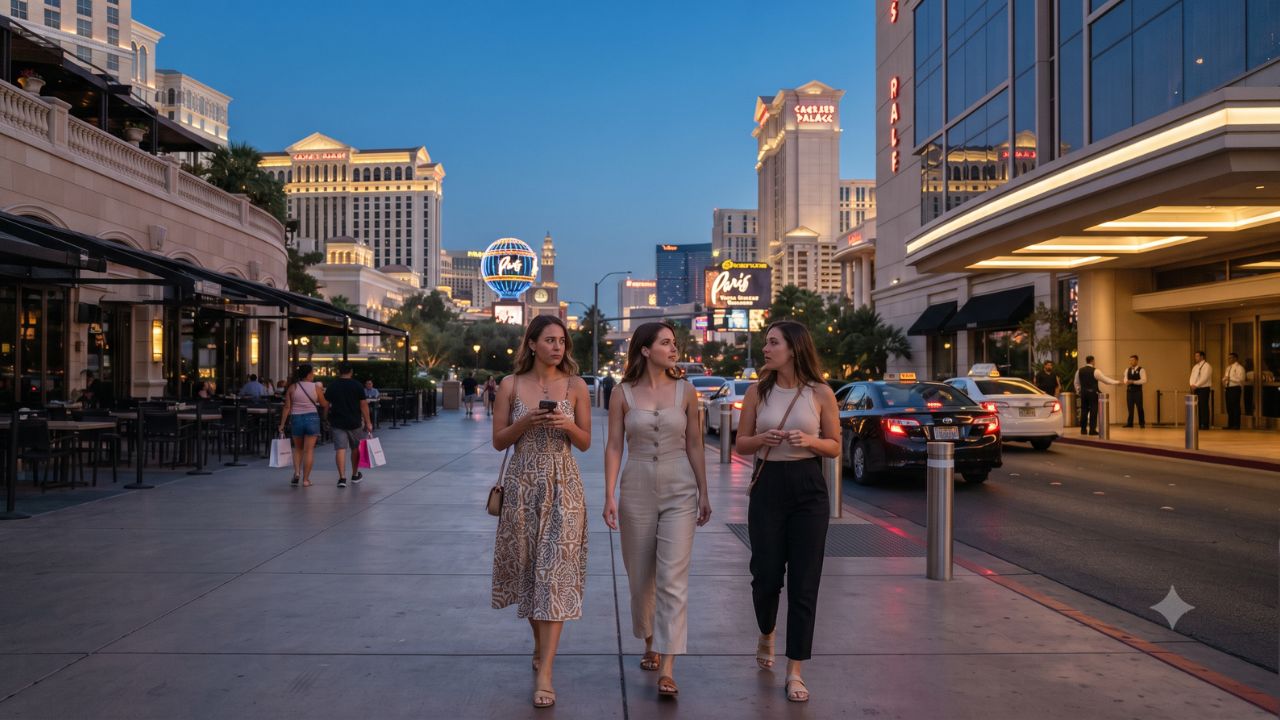
- Las Vegas, Nevada: The entertainment capital faces an acute supply shock, triggered by the retreat of its essential Canadian feeder market. Canadian carriers eliminated an estimated 82,000 airline seats destined for Harry Reid International Airport in the first quarter of 2026 alone. Consequently, overall visitor volumes dropped to levels not recorded since the 2010 post-recession period (excluding pandemic lockdowns). Without high-spending international casino and retail patrons, local operators face sharp yield compression across resort properties.
- Miami and New York City: Classified by market analysts as bearing "Very High" vulnerability to overseas downturns, both metropolitan areas are suffering from a retreating short-term rental (STR) sector. National STR demand dipped 2.3% in August 2026. Because foreign visitors traditionally reserve vacation rentals weeks in advance and maintain longer durations of stay, urban hosts in Miami and New York are experiencing severe occupancy drops. Similar stress is visible in secondary exposed gateways, including Los Angeles, San Francisco, and Honolulu.
- Orlando, Florida: Central Florida’s theme park corridor is directly exposed to global foreign exchange pressures. The sustained strength of the U.S. dollar against European and Latin American currencies transformed family vacations into prohibitive luxuries for foreign middle-class visitors. This drop in purchasing power manifested directly in municipal coffers, with Orange County and municipal authorities reporting double-digit percentage drops in local hotel occupancy tax collections.
- Northern Border Crossings: The downturn extends beyond airports into maritime and vehicular border corridors. Washington State and upstate New York experienced steep drops in Canadian drive-in and ferry traffic. Regional marine transit providers, including Clipper Travel, instituted corporate layoffs, while municipal ferry networks implemented operational schedule cuts to counter disappearing cross-border day trips.
Tourism Ledger Breakdown: Inbound Spending, Aviation Yields, and Local Receipts
Examining official data compiled by the NTTO and the U.S. Travel Association reveals the divergence between airfare receipts and physical destination spending:
| Sector & Indicator | August 2026 Performance | Year-on-Year Trend | Strategic Economic Mechanism | Core Operational Vulnerability |
|---|---|---|---|---|
| Domestic Destination Spending | $10.8 billion | −9.0% YoY | Covers lodging, food, local transport, recreation, and retail | Direct loss of high-yield, multi-day international visitor spending |
| Total Inbound Travel Receipts | $19.9 billion | −4.9% YoY | Overall export valuation of inbound foreign visitor transactions | Shrinking export earnings across the broader services balance of trade |
| Outbound American Spending | $19.7 billion | +0.5% YoY | Outbound leisure and corporate travel spending by US citizens abroad | Record outflow leaves an August tourism surplus of just $157 million |
| U.S. Airline Passenger Fares | $2.8 billion | −3.0% YoY | International passenger revenues collected by US-flagged air carriers | Airline capacity cuts support ticket yields despite 11.8% passenger drop |
| Education & Medical Travel | $6.4 billion | +3.0%+ YoY | Non-discretionary exports: university tuition, healthcare, seasonal labor | Anchor sector generating 32% of total August international travel receipts |
| Resort Lodging RevPAR | Industry Benchmark | −3.5% YoY | Revenue per available room across luxury and coastal resort hotels | Contrasts with 2.0% RevPAR growth across urban domestic business hotels |
| Short-Term Rental Demand | National Metric | −2.3% YoY | Overall reservation nights across vacation and alternative rentals | Disproportionately hits international gateways like Miami and NYC |
The aviation data exposes an interesting paradox. While physical arrivals dropped 11.8%, international passenger fare revenues collected by U.S.-flagged carriers fell by only 3% to $2.8 billion. Major legacy airlines protected ticket yields by executing tactical capacity discipline—canceling underperforming routes and reducing frequencies to maintain high seat prices. Additionally, stable corporate premium-cabin demand masked the sharper contraction in economy leisure seats.
Counter-Cyclical Drivers: Medical, Academic, and Emerging Source Markets
A catastrophic drop in overall export revenues was averted primarily due to non-discretionary, purpose-driven travel categories. Expenditure across international higher education, specialized medical tourism, and temporary worker logistics expanded by more than 3% in August, generating $6.4 billion. Representing 32% of total U.S. travel exports for the month, the annual August university intake brought essential non-negotiable living and tuition payments that stabilized the services trade balance.
Furthermore, specific emerging and regional origin markets completely bypassed the broader downturn. While Western European and East Asian leisure travel contracted, arrivals from select markets soared well above pre-pandemic 2019 baselines:
- Mexico: Air arrivals reached an exceptional 148% of 2019 levels, driving transborder aviation links.
- India: Air passenger arrivals tracked at 126% of historical 2019 benchmarks, solidifying its role as a premier high-growth source market.
- Colombia: Inbound passenger traffic registered at 124% of 2019 performance, sustaining South American feeder lines into Florida and Texas.
Expert Analysis: Currency Hurdles, Yield Shifting, and Corporate Buffers
The structural retreat of the international tourist forces a fundamental re-evaluation of hospitality business models across the United States.
For travelers booking this route, the direct consequence is that international guests face substantial currency exchange hurdles that make on-the-ground American travel exponentially more expensive. When the U.S. dollar remains stubbornly elevated against the Euro, British Pound, Canadian Dollar, and Brazilian Real, discretionary expenses—such as dining out, rental cars, theme-park admission, and local retail—become prohibitive. International travelers are either truncating their lengths of stay from two weeks to seven days, substituting full-service resort stays for midscale suburban hotels, or bypassing the United States entirely in favor of currency-discounted destinations in Southern Europe, Southeast Asia, or Mexico.
The pricing pressure this creates means that domestic urban hotels must increasingly depend on corporate business travel and group conventions to offset collapsing international leisure volume. In August 2026, while resort RevPAR contracted by 3.5%, urban and airport hotels managed a 2.0% RevPAR increase, buoyed by domestic business travelers that lifted overall national room demand by a modest 0.8%.
Hotels are relying on corporate commitments as an economic buffer for the upcoming winter. Mid-September tracking figures show corporate bookings pacing ahead of 2025 by 5.2% for October, 7.7% for November, and 11.2% for December, with fourth-quarter group room nights up 4.2%. However, corporate travelers cannot fully replace the multi-room, multi-week retail spending that foreign leisure families traditionally generate across resort corridors.
Actionable Traveler Guidance: Navigating the Changing Hospitality Grid
The recalibration of U.S. inbound tourism creates specific opportunities and planning considerations for travelers:
- Capitalize on Leisure Destination Rate Softening: With international demand falling, luxury resorts in destinations like Orlando, Miami, and Las Vegas are facing inventory pressure. Travelers should look for promotional packages, waived resort fees, and complimentary dining credits, particularly for midweek stays during the autumn shoulder season.
- Anticipate Tight Airline Capacity: Do not expect falling international visitor counts to translate into cheap international airfares. Because carriers have cut seat capacity—exemplified by the 82,000 seats removed from Canadian-Las Vegas routes—flight inventory remains tight. Book transatlantic and transpacific sectors early to avoid high yield-managed ticket pricing.
- Monitor Municipal Tax Adjustments: Cities experiencing drops in tourism tax revenues may adjust municipal surcharges, parking levies, or local hotel bed taxes to meet budget deficits. Always verify the total all-in price of hotel reservations, including municipal tax lines, prior to finalizing non-refundable stays.
- Leverage Urban Alternative Accommodations: As urban short-term rental hosts face lower international occupancy in cities like New York and Miami, booking windows are opening up. Travelers can frequently negotiate favorable extended-stay rates for multi-week corporate or remote-work accommodations directly on platform channels.
Key Takeaways
- Sharp Domestic Expenditure Drop: On-the-ground spending by foreign visitors across U.S. hotels, dining, and retail fell 9% to $10.8 billion in August 2026, driven by an 11.8% drop in overseas arrivals.
- Narrowing Tourism Trade Surplus: American travelers spent $19.7 billion abroad, leaving the United States with a razor-thin monthly travel trade surplus of just $157 million.
- Severe Localized Impacts: Las Vegas suffered from 82,000 lost Canadian airline seats, while Orlando experienced double-digit percentage drops in local hotel tax receipts due to the strong dollar.
- Aviation Yield Insulation: U.S. airline passenger receipts fell only 3% to $2.8 billion despite double-digit arrival drops, as carriers implemented capacity cuts to defend ticket prices.
- Resilient Origin Markets: Defying the global slump, arrivals from Mexico (148% of 2019 levels), India (126%), and Colombia (124%) established historic highs.
FAQ: US International Tourism Drop and Economic Impact 2026
Why did US international tourism spending decline in August 2026?
Inbound spending declined primarily due to an 11.8% drop in overseas arrivals, driven by the strong U.S. dollar, macroeconomic pressures in key foreign markets, and airline seat capacity reductions.
How does the drop in foreign visitors affect local city economies?
Because international visitors stay longer and spend heavily on hotels, dining, local transit, and retail, their absence caused a 9% drop in on-the-ground spending, eroding municipal hotel tax revenues in hubs like Orlando and Las Vegas.
Which countries are sending more travelers to the US despite the downturn?
Mexico, India, and Colombia are outperforming historical records, with air arrivals reaching 148%, 126%, and 124% of their pre-pandemic 2019 benchmarks respectively.
What is the current status of the US travel trade balance?
The monthly U.S. travel trade surplus narrowed to $157 million in August 2026 as Americans spent $19.7 billion abroad, nearly offsetting the $19.9 billion spent by foreign visitors in the United States.
[When international visitor volume recedes, the destinations that endure are those that adapt their pricing before the rooms sit empty.]
Related Travel Guides
- FIFA World Cup 2026 Travel Surge: Host City Flight Bookings, FIFA PASS Visas, and Transit Logistics
- Expedia 2027 Travel Trends: Gothic Getaways, Trip Snacking, and Regional Escapes Reshape Global Tourism
- Thanksgiving 2026 Short-Term Rental Surge: University Towns Outpace Metros as College Football Rivalries Squeeze Lodging
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Raushan Kumar
Founder & Lead Developer
Full-stack developer with 11+ years of experience and a passionate traveller. Raushan built Nomad Lawyer from the ground up with a vision to create the best travel and law experience on the web.
Learn more about our team →