French Social Protests Threaten Long-Haul Tourism: Inbound Vulnerabilities in Thailand, Indonesia, and Mauritius
Escalating domestic protests and budget pressures in France threaten long-haul tourism receipts across highly exposed destinations including Thailand, Indonesia, and Mauritius.
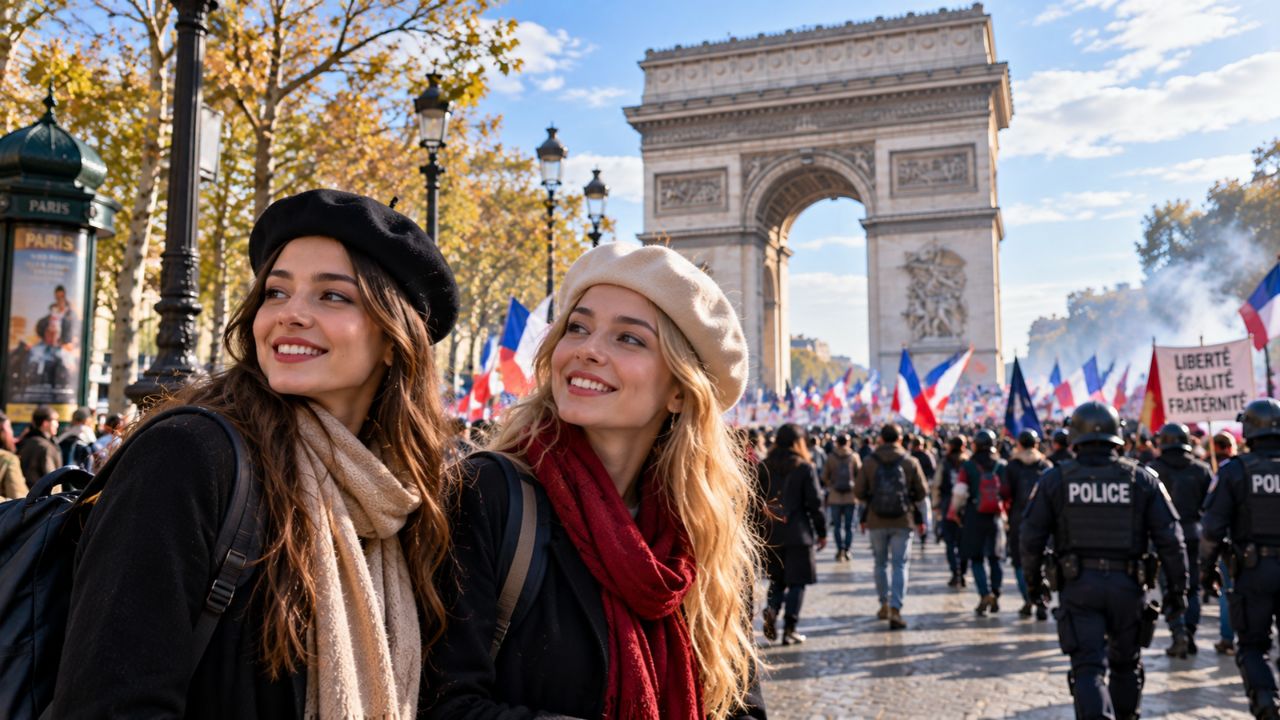
Image generated by AI
With outbound French travelers generating over 9.27 million visits to Spain, 5.7 million arrivals to Morocco, and nearly 23% of all inbound tourism in Mauritius, intensifying civil protests and economic instability across France threaten to trigger a sharp contraction in long-haul discretionary holiday spending. As trade union demonstrations and transport strikes disrupt metropolitan France in October 2026, tour operators from Bangkok to Port Louis face growing concerns that weakened household consumer confidence will force French families to truncate holiday itineraries, slash excursion budgets, or delay winter holiday commitments.
Domestic Economic Squeeze and Long-Haul Discretionary Retrenchment
The transmission mechanism connecting street demonstrations in Paris to hotel occupancy in Southeast Asia lies in household disposable income and consumer sentiment. Across France, nationwide labor unrest and legislative disputes over budgetary tightening have amplified domestic financial anxiety. According to national tourism development analyses published by Atout France, discretionary holiday spending serves as the immediate buffer when French households anticipate domestic austerity or economic slowdowns.
In Thailand, commercial operators note that European demand faces dual compounding headwinds. Inbound tourism from Western Europe was already experiencing friction from ongoing Middle East airspace closures and elevated long-haul aviation surcharges, as highlighted in Bangkok Post industry reports. Industry monitors at the Tourism Authority of Thailand note that when long-haul flight costs rise while domestic financial sentiment weakens, French holidaymakers rarely cancel trips outright; instead, they alter booking behaviors. Travelers shift from four-star resort stays to three-star guesthouses, eliminate guided multi-day excursions, and defer booking windows from four months down to two weeks before departure.
This behavior creates distinct operational exposure depending on how heavily a destination relies on French arrivals. In island economies like Mauritius and Seychelles, where French holidaymakers represent major volume drivers, even a minor downward revision in per-passenger spending creates immediate revenue deficits for beachfront resorts, local catamaran operators, and private vehicle hire companies.
Continental and Long-Haul Market Exposure Across Eleven Economies
Official statistical records from national immigration ministries establish the precise baseline exposure of eleven global destinations catering to French travelers. The reliance varies from peripheral exposure in the Maldives to systemic dependence in North Africa and the Indian Ocean.
The table below synthesizes the reported visitor figures, reporting periods, market ranks, and economic exposure profiles across the monitored destination markets as of October 2026.
| Destination Country | French Inbound Volume | Reporting Period & Source Agency | Market Rank & Share | Primary Economic Risk Vector |
|---|---|---|---|---|
| Spain | 9,277,638 arrivals | Jan–Aug 2026 (INE Provisional) | Rank 2; major European volume | Shortened hotel stays; retreat to self-catering |
| Morocco | >5,700,000 tourists | Full Year 2025 (ONMT) | Rank 1; ~29% total arrivals | Compression of medina riad and excursion spending |
| United Kingdom | 3,135,000 visits | Full Year 2025 (VisitBritain) | £1.67 billion total spend | Channel crossing deferrals; London hotel rate resistance |
| Portugal | 2,160,000 overnight stays | Jan–Jul 2026 (Turismo de Portugal) | Rank 5; 6.7% foreign guest nights | Guest night compression in Lisbon and the Algarve |
| Viet Nam | 276,817 arrivals | Jan–Sep 2026 (VNAT) | 19,824 arrivals in Sep alone | Heritage tour package cancellations in Indochina |
| Mauritius | 153,048 arrivals | Jan–Jun 2026 (Statistics Mauritius) | Rank 1; ~22.9% of 668,471 total | Severe resort RevPAR decline across island economy |
| Sri Lanka | 78,860 arrivals | Jan–Sep 2026 (SLTDA) | Rank 7 foreign source market | Delay of bespoke cultural triangle and hill country tours |
| Indonesia | 58,018 visits | August 2026 single-month (Min. Tourism) | Significant summer holiday segment | Bali villa booking cancellations and shorter dive stays |
| Seychelles | 41,409 visitors | Full Year 2025 (Central Bank Seychelles) | ~10.4% share of 398,841 total | Luxury resort vacancy during European winter escape |
| Maldives | 39,116 arrivals | Through Oct 18, 2026 (Min. Tourism) | 2.3% of national arrivals | Highly localized impact restricted to select dive resorts |
| Thailand | Monitored Segment | October 2026 Trade Assessment | Core European winter market | Compounding pressure alongside Middle East flight detours |
The geographic distribution demonstrates that while short-haul destinations such as Spain and Portugal process massive raw numbers, their proximity provides a geographic buffer. When long-haul journeys to Southeast Asia become cost-prohibitive, French travelers often substitute long-distance flights with drive-to or budget-airline getaways across the Iberian Peninsula. Conversely, long-haul destinations like Viet Nam, which secured 276,817 French arrivals through September 2026, lack low-cost substitution options and face direct cancellations if intercontinental airfares collide with tighter household budgets.
Expert Analysis: Yield Degradation, Currency Frictions, and Carrier Seat Reallocation
For travelers booking these international corridors, the direct consequence of French economic retrenchment is an alteration in airline seat availability and promotional fare structures. European legacy carriers operating direct trunk routes from Paris Charles de Gaulle (CDG) and Orly (ORY) to Bangkok Suvarnabhumi (BKK), Denpasar (DPS), and Sir Seewoosagur Ramgoolam International (MRU) rely heavily on high-yield French leisure passengers to sustain forward cabin profitability. When forward bookings soften, airlines do not immediately ground wide-body aircraft; instead, they slash economy yields and reallocate promotional inventory to secondary European feeder hubs in Germany, the Netherlands, and Scandinavia.
The pricing pressure this creates means hospitality operators in long-haul markets cannot rely on uniform pricing matrices. In Mauritius, where French residents generated 153,048 visits out of 668,471 total arrivals in the first half of 2026 alone, resorts face high fixed operational overheads. To prevent catastrophic occupancy drops, local hotel associations will be forced to roll out tactical discounts, complimentary meal plans, and waived single supplements. However, this discounting damages overall Revenue Per Available Room (RevPAR), curtailing capital reinvestment into property renovations.
In parallel, cross-border corporate intelligence tracked by VisitBritain confirms that exchange rate volatility introduces secondary friction. While British attractions captured £1.67 billion across 3.135 million French visits in 2025, any post-protest depreciation of the euro against the pound sterling or the US dollar immediately inflates on-the-ground expenses for French holidaymakers in dollar-pegged markets like the Maldives and Southeast Asia.
For destination management companies in Sri Lanka and Indonesia, the strategic mandate requires rapid market diversification. Sri Lanka’s 78,860 French arrivals through the third quarter of 2026 place France firmly as the country's seventh-largest inbound generator. If French bookings stall during the critical November-to-January peak booking window, inbound agencies must pivot marketing expenditure toward alternative outbound markets such as India, Poland, and Australia to fill regional capacity gaps.
Key Takeaways
- High Exposure in Mauritius and Morocco: France represents nearly 29% of all international tourists in Morocco and 22.9% of total arrivals in Mauritius, making both economies uniquely vulnerable to French domestic economic shocks.
- Asian Long-Haul Vulnerability: Inbound operators in Viet Nam (276,817 arrivals through September) and Sri Lanka (78,860 arrivals) face order cancellations and shorter itineraries if French households curtail holiday budgets.
- European Substitution Shift: Continental short-haul destinations like Spain (9.27M French arrivals through August) and Portugal (2.16M guest nights through July) may capture diverted demand as travelers abandon expensive intercontinental routes.
- Airline Inventory Discounting: Carriers facing softened demand on Paris departure routes will likely release aggressive promotional inventory to secondary European gateways to maintain long-haul load factors.
- Absence of Confirmed Direct Losses: Official statistical data establishes current market exposure and historical volume, while confirmed economic losses attributable directly to the October protests remain subject to upcoming booking cycles.
FAQ: French Tourism Disruptions and Global Travel 2026
Have international airlines cancelled flights from Paris due to the protests?
Commercial long-haul flights from Paris Charles de Gaulle and Orly continue scheduled operations. Intermittent domestic transport strikes cause airport rail link delays, but intercontinental airline flight schedules remain largely intact.
Why is Mauritius more vulnerable to French economic shifts than the Maldives?
France accounts for approximately 22.9% of all inbound tourists in Mauritius, representing its single largest market. In contrast, French arrivals constitute only 2.3% of visitors in the Maldives, spreading commercial risk across other global source markets.
Are hotel prices in Thailand expected to drop for European travelers?
Hotels targeting European leisure visitors may introduce value-added promotions and discounted shoulder-season rates if forward booking windows from France and Western Europe continue to lag historical averages.
How does Middle East airspace disruption intersect with French travel demand?
Rerouted flight paths around Middle East conflict zones have increased flight durations and fuel surcharges on routes to Southeast Asia, compounding domestic financial hesitation for long-haul French travelers.
Global tour operators and airline revenue managers must closely track French forward booking curves through the fourth quarter to anticipate winter yield shifts.
Related Travel Guides
Vietnam Tourism Growth Outpaces Singapore, Thailand, and Cambodia in 2026
The 10 Best Budget Destinations in Southeast Asia, According To Reddit
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Raushan Kumar
Founder & Lead Developer
Full-stack developer with 11+ years of experience and a passionate traveller. Raushan built Nomad Lawyer from the ground up with a vision to create the best travel and law experience on the web.
Learn more about our team →