China Cements Position as World's Second-Largest Business Travel Market as Asia Pacific Drives Global Corporate Spending Toward $2 Trillion
China drives 60% of Asia Pacific corporate travel spending as regional investment expands 7.5%, propelling global business travel toward a $2 trillion milestone.
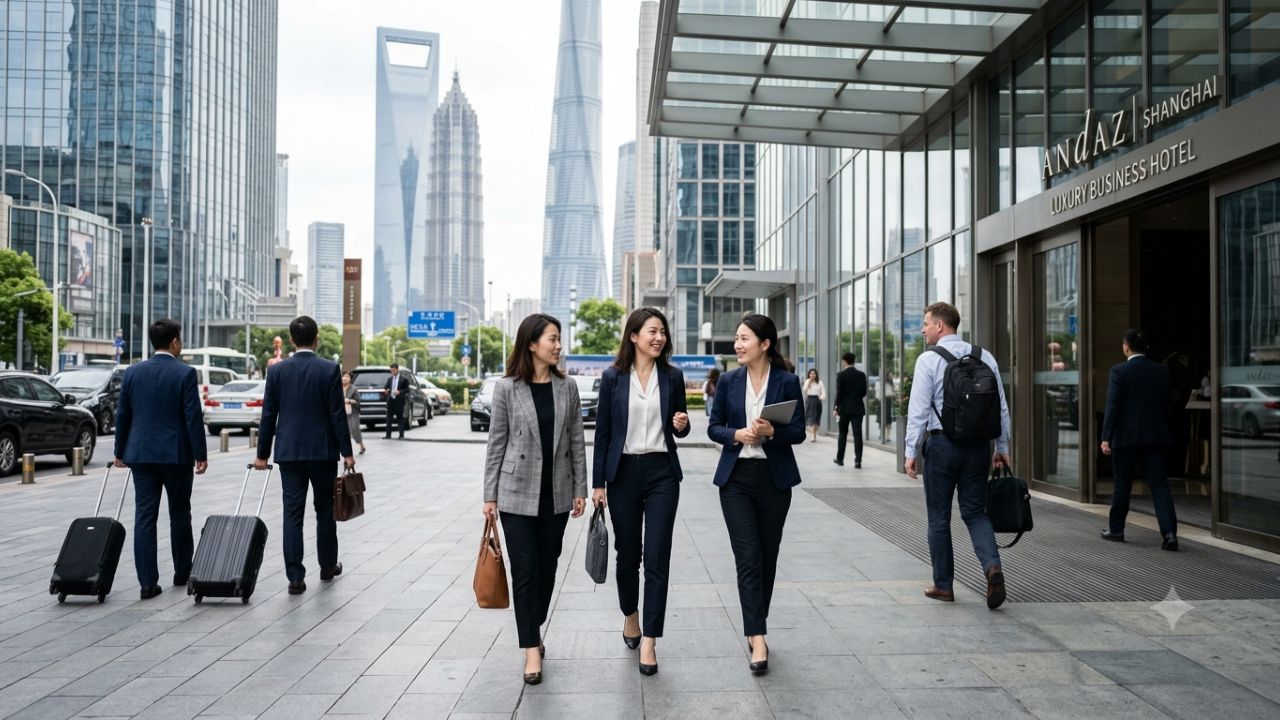
Asia Pacific powers the global business travel recovery, accounting for 40% of worldwide corporate mobility expenditure.
China has solidified its standing as the world’s second-largest business travel market, generating approximately 60% of all corporate travel expenditure across the Asia-Pacific region as global spending accelerates toward a historic $2 trillion valuation by 2030. According to official industry data released by the Global Business Travel Association (GBTA), worldwide corporate travel expenditure is projected to surpass US$1.7 trillion in 2026 and rise a further 6% to reach US$1.8 trillion in 2027. Fueling this expansion is the Asia-Pacific corridor, which now commands 40% of total international business travel expenditure and 35% of all global professional journeys, establishing the eastern hemisphere as the undisputed command centre of worldwide executive mobility.
The findings, presented by GBTA Chief Executive Officer Suzanne Neufang during TravelDaily’s Business Travel Conference keynote titled "Business Travel at an Inflection Point: The Economics, Outlook and Trends Shaping What’s Next in APAC and Beyond" on 23 September 2026, reveal an industry executing a profound structural pivot. Corporate mobility is no longer sprinting through the volatile, reactive rebound that characterized post-pandemic reopening cycles. Instead, enterprise travel programs are shifting into a disciplined, value-governed expansion phase, balancing aggressive commercial expansion in Asian production hubs against severe airfare and hotel price inflation.
                           ┌──────────────────────────────────────────────┐
                           │    Global Corporate Travel Spend ($1.7T+)    │
                           └──────────────────────┬───────────────────────┘
                                                  │
                 ┌────────────────────────────────┴───────────────────────────────┐
                 ▼                                                               ▼
        ┌──────────────────────────────────┐                    ┌──────────────────────────────────┐
        │   Asia-Pacific Region (40%)      │                    │     Rest of the World (60%)      │
        ├──────────────────────────────────┤                    ├──────────────────────────────────┤
        │ • 40% of global expenditure      │                    │ • North America (US #1 market)   │
        │ • 35% of global travel volume    │                    │ • Western and Central Europe     │
        │ • Projected +7.5% growth in 2026 │                    │ • Middle East & Latin America    │
        └─────────────────┬────────────────┘                    └──────────────────────────────────┘
                          │
         ┌────────────────┴────────────────┐
         ▼                                 ▼
┌──────────────────┐             ┌──────────────────┐
│   China (60%)    │             │ Other APAC (40%) │
├──────────────────┤             ├──────────────────┤
│ • World #2 spend │             │ • Japan, India   │
│ • +6% in 2026    │             │ • Australia, SEA │
└──────────────────┘             └──────────────────┘
Asia Pacific Commands the Global Corporate Travel Landscape
Asia Pacific has widened its lead over North America and Europe to become the primary engine of international commercial travel. The region accounts for roughly US$4 out of every US$10 spent globally on corporate flights, high-speed rail, corporate lodging, and client entertainment.
On pure volume, APAC travelers undertake approximately 35% of all professional journeys completed worldwide. Industry forecasts indicate that corporate travel expenditures across the Asia-Pacific zone will expand by approximately 7.5% throughout 2026. While economic headwinds and tightening corporate governance may prompt slight moderation going into 2027, annual regional spending gains are projected to remain securely above 7%.
This resilience is underpinned by the density of cross-border supply chains, manufacturing networks, and financial syndicates linking East Asian manufacturing hubs with Southeast Asian distribution centers. Unlike Western corporate environments where remote work protocols permanently eroded regional commuter flights, Asian business customs place a decisive premium on physical meetings, on-site supplier audits, and personal relationship development.
China's Dominance Across the Regional Spending Matrix
Within the Asia-Pacific theatre, the People's Republic of China functions as the primary economic anchor. China accounts for approximately 60% of all corporate travel expenditure recorded across the entire region, securing its unchallenged rank as the world's second-largest corporate travel market behind the United States.
Projections from GBTA indicate that enterprise travel expenditures originating within China will climb by nearly 6% across 2026. This performance carries immediate consequences for global travel suppliers:
- Airlines and Route Networks: Transpacific and Eurasian flight frequencies depend heavily on Chinese business demand, with high-yield business class and premium economy cabins anchored by mainland manufacturing executives and multinational procurement directors.
- Global Hospitality Chains: International hotel brands across Tier-1 and Tier-2 Chinese urban centers—including Shanghai, Beijing, Shenzhen, and Guangzhou—rely on corporate negotiated rates for base occupancy throughout weekdays.
- Travel Management Companies (TMCs): Corporate travel agencies are rapidly integrating China's domestic payment ecosystems (such as WeChat Pay, Alipay, and local enterprise expense cards) with global booking tools to capture high-frequency corporate mobility.
       Corporate Travel Expenditure Growth Curve (2026–2030 Horizon)

  $2.0T ────────────────────────────────────────────────────────────► Projected 2030
                                                      ┌───────────┐
  $1.8T ───────────────────────────────► 2027 Forecast│  Global   │
                         ┌───────────┐                │ Corporate │
  $1.7T ──────► 2026 Base│  Global   │                │ Mobility  │
        ┌───────────┐    │ Corporate │                │  Surge    │
        │  Global   │    │ Mobility  │                └───────────┘
        │ Corporate │    └───────────┘
        │ Mobility  │
        └───────────┘
The table below summarizes the key financial milestones, market distributions, and growth trajectories shaping the international corporate travel market through 2030:
| Market Segment / Benchmark | Projected Metric | Strategic and Economic Impact |
|---|---|---|
| Global Corporate Travel Spend (2026) | > US$1.7 Trillion | Marks the definitive milestone establishing pre-pandemic baseline recovery |
| Global Corporate Travel Spend (2027) | ~ US$1.8 Trillion (+6%) | Steady, measured expansion driven by commercial diplomacy and enterprise events |
| Global Long-Term Benchmark (2030) | > US$2.0 Trillion | Unprecedented milestone demonstrating the financial scale of global professional mobility |
| Asia-Pacific Regional Market Share | ~ 40% of Global Spend | World's largest regional corporate travel market by financial expenditure |
| Asia-Pacific Journey Volume | ~ 35% of Global Trips | World's highest concentration of business-related flight and rail movements |
| Asia-Pacific Annual Growth Rate | 7.5% (2026) / >7% (2027) | Highest sustained regional expansion rate across the global travel economy |
| China Global Ranking | World #2 Market | Second only to the United States in domestic and cross-border corporate budgets |
| China Regional Share | ~ 60% of APAC Total | Primary demand generator for regional airlines, hotels, and enterprise car rentals |
| China 2026 Growth Rate | ~ 6% Projected Rise | Outperforms broader economic expansion rates through manufacturing and trade ties |
The Inflation Disparity: Spending Outpaces Trip Frequency
A defining reality illuminated in Suzanne Neufang’s address is the expanding structural disconnect between rising financial expenditures and real trip volume. While headline corporate travel expenditure figures are reaching historic peaks, overall ticket and room counts are growing at a markedly slower rate.
Enterprise travel budgets are absorbing substantial cost pressures across multiple operational verticals:
- Commercial Airfare Rates: Tight capacity constraints, supply chain delivery delays at commercial planemakers, and elevated sustainable aviation fuel (SAF) mandates have locked average corporate airfares into higher price bands.
- Premium Lodging Tariffs: Average daily rates (ADR) at business-class hotels across major commercial capitals remain elevated due to commercial property debt costs, staff wage adjustments, and energy costs.
- Ancillary Ground Logistics: Ground transportation, airport transfer fees, and corporate event hosting costs have increased steadily across major metropolitan centers.
                  Cost Inflation vs. Travel Volume Divergence

     ┌────────────────────────────────────────────────────────┐
     │  Corporate Travel Expenditure (Rising Faster: +6%–7%)  │  ▲
     └────────────────────────────────────────────────────────┘  │ Inflation Gap
     ┌────────────────────────────────────────────────────────┐  │ (Higher costs
     │  Actual Journey Volume (Moderate Growth: +2%–3%)       │  ▼  per journey)
     └────────────────────────────────────────────────────────┘
For travel procurement directors and corporate travel managers, this disparity requires a complete recalculation of travel return on investment (ROI). Companies can no longer measure travel program vitality simply by tracking total gross spend; they must evaluate the strategic commercial yield of every individual trip taken.
Strategic Realignment: In-Person Value Governs Enterprise Budgets
Despite macroeconomic volatility, currency fluctuations, and geopolitical friction across international trading corridors, global enterprises continue to protect their core travel allocations. Virtual conferencing tools have permanently replaced routine internal administrative check-ins, but in-person interaction remains an indispensable requirement for revenue generation.
Executive leadership teams recognize that face-to-face engagements generate tangible commercial advantages that digital channels cannot replicate:
- Complex Cross-Border Negotiations: Multi-party supply agreements, joint venture formations, and contract arbitrations in Asian markets require direct, interpersonal engagement to establish mutual accountability.
- Enterprise Sales and Account Retention: Securing multi-year enterprise contracts continues to correlate directly with on-site executive briefings and client discovery workshops.
- Operational Audits and Quality Assurance: Advanced manufacturing hubs throughout China and Southeast Asia necessitate physical facility inspections by engineering teams to maintain regulatory compliance.
Rather than curbing corporate travel wholesale, organizations are consolidating itineraries—encouraging executives to combine client visits, trade conferences, and supplier audits into single, multi-day itineraries that maximize productivity per flight segment.
What This Means for Corporate Travel Managers and Suppliers
The consolidation of Asia Pacific as the focal point of worldwide business travel carries immediate operational implications for enterprise travel buyers and travel suppliers:
- Strategic Supplier Sourcing in APAC: Global travel management programs must prioritize negotiated hotel rates and airline corporate discount programs tailored to Asian flight corridors, where seat availability on key trunk routes remains constrained.
- Dynamic Policy Enforcement: Travel managers are shifting toward dynamic budgeting, allowing booking caps to adjust automatically to seasonal surges in regional flight fares and hotel ADR rather than adhering to rigid, static city-per-diems.
- Duty of Care and Geopolitical Tracking: With cross-border corporate movement intensifying across mainland China and Southeast Asia, risk management protocols must incorporate automated flight disruption tracking, localized medical assistance, and real-time transit advisories.
Frequently Asked Questions
What rank does China hold in global business travel spending?
China ranks as the world's second-largest business travel market, trailing only the United States in total corporate travel expenditure.
What percentage of Asia Pacific corporate travel spending belongs to China?
China generates approximately 60% of all corporate travel expenditure within the Asia-Pacific region, making it the primary driver of regional business travel demand.
When is global corporate travel spending projected to reach $2 trillion?
According to GBTA projections, worldwide business travel spending is expected to surpass US$1.7 trillion in 2026, reach US$1.8 trillion in 2027, and exceed US$2.0 trillion by 2030.
Why is corporate travel spending growing faster than trip volume?
Higher average airfares, elevated hotel room rates, and increased ground transportation costs mean corporations are spending more per journey without necessarily booking a proportionally higher number of trips.
Related Travel Guides
- Expedia Group Unlocks US$100 Billion Travel Spending Opportunity With New Audience Marketing Framework 2026
- US Corporate Travel Surges in October 2026: Orlando, Las Vegas, and Nashville Lead Group Meeting Boom
- Japan Corporate Tourism Boom 2026: Blending MICE Events with Cultural Escapes in Tokyo and Osaka
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Kunal K Choudhary
Co-Founder & Contributor
A passionate traveller and tech enthusiast. Kunal contributes to the vision and growth of Nomad Lawyer, bringing fresh perspectives and driving the community forward.
Learn more about our team →