Global Aviation Services Market to Double to US$422B by 2045: Airbus Forecast Details Severe Fleet Maintenance and Crew Deficits
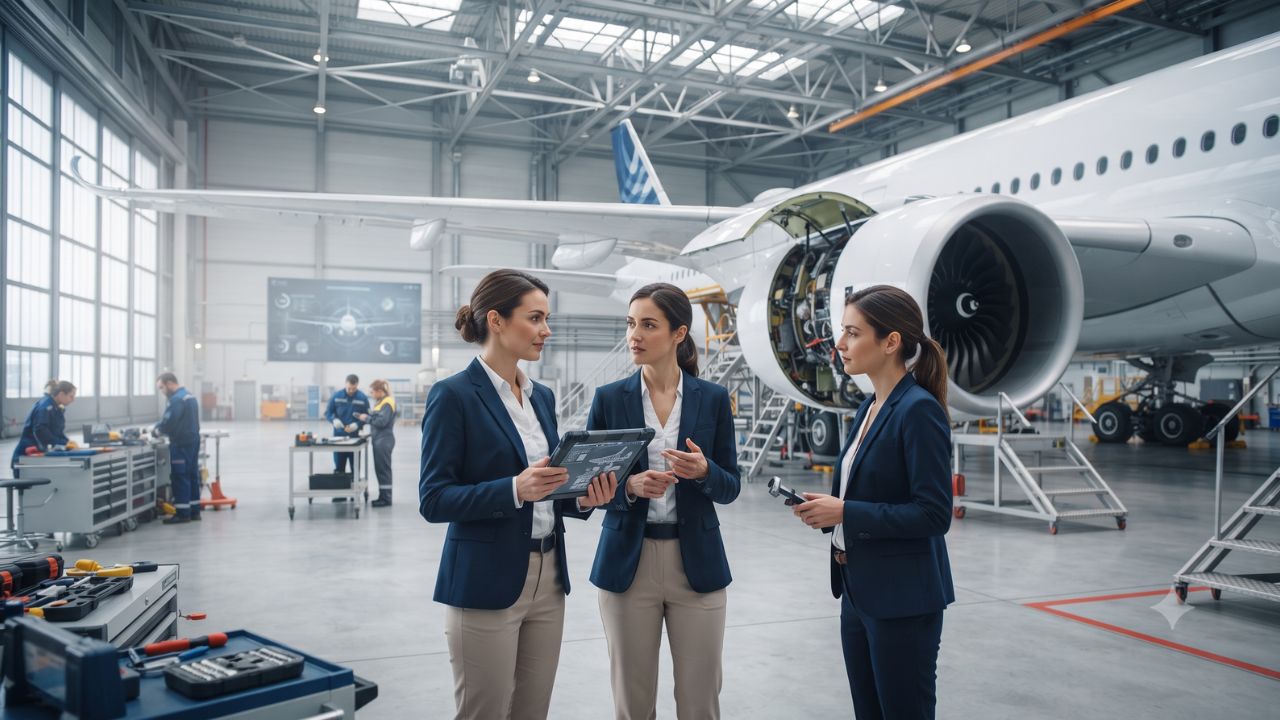
Projecting an annual commercial aviation services valuation surging 101.9% from US$209 billion in 2026 to US$422 billion by 2045, Airbus released its Global Services Forecast in Toulouse, France, on 14 October 2026. Underpinned by an expanding worldwide commercial fleet of 45,550 aircraft and approximately 10 billion annual passenger journeys, the 20-year outlook establishes that maintaining, upgrading, and operating passenger airframes will require 2.44 million newly qualified aviation professionals. Compounding at an annual growth rate of 3.8%, the services sector will expand in parallel with 42,060 expected new aircraft deliveries, confronting airlines with acute structural demands for skilled maintenance personnel, engine overhaul capacity, and digital predictive infrastructure.
The macro forecast arrives during an era of significant near-term operating strain. Supply chain research published on 24 June 2026 confirmed persistent engine durability bottlenecks, severe spare parts shortages, and backlogged maintenance repair organizations (MROs), prompting an industry cooperation pact on 25 June to pool technical assets. While global passenger traffic dipped 0.8% in August 2026 against a 0.3% capacity increase, and international tourist arrivals reached 690 million in the first half of 2026 (+0.4%), the long-term fundamentals point toward an unprecedented operational footprint centered in emerging aviation corridors.
Deconstructing the US$422 Billion Annual Services Economy
The Airbus outlook defines commercial services across aircraft with more than 100 passenger seats and cargo freighters exceeding 10 tonnes payload. The sector's projected US$213 billion net expansion between 2026 and 2045 is heavily concentrated in heavy engineering, powertrain overhauls, and regulatory airworthiness compliance:
- Engine and Component Maintenance (US$217 Billion): Comprising more than half of the total 2045 market, advanced turbine inspections, hot-section shop visits, and avionics component repairs represent the single largest expenditure category as high-bypass turbofans demand tighter servicing intervals.
- Flight and Ground Operations Support (US$104 Billion): Encompasses flight dispatch, dispatch planning software, fuel optimization programs, and ground handling logistics necessary to turnaround multi-fleet schedules.
- Airframe Maintenance and Inspections (US$36 Billion): Covers structural heavy checks (C and D checks), corrosion monitoring, composite repairs, and scheduled line maintenance.
- Cabin Modifications and Interior Upgrades (US$21 Billion): Driven by passenger expectations for retrofitted seating, high-density configurations, premium economy insertions, and modern inflight galleys.
- Digital Systems and Inflight Connectivity (US$27 Billion): Projecting the fastest annual expansion at 5.3%—nearly tripling over the forecast window—via predictive telemetry, automated fault diagnostics, and satellite broadband.
- Aviation Training and Skill Development (US$17 Billion): Dedicated flight simulators, technician licensing programs, and recurrent training curricula.
Collectively, maintenance, operations support, and heavy inspections account for US$357 billion, or 84.6% of the entire 2045 commercial aviation services market.
Sectoral Spending Projections and Human Capital Requirements by 2045
The table below contrasts the commercial expenditure categories and cumulative workforce deployment targets established in the Airbus Global Services Forecast:
| Operational Services Sector | Projected 2045 Annual Value | Market Share Percentage | Compound Annual Growth Rate (CAGR) | Strategic Operational Function |
|---|---|---|---|---|
| Engine & Component Maintenance | US$217 billion | 51.4% | ~3.8% | Turbofan overhauls, life-limited parts, avionics |
| Operations & Flight Support | US$104 billion | 24.6% | ~3.6% | Ground handling, route optimization, operational dispatch |
| Airframe Heavy Maintenance | US$36 billion | 8.5% | ~3.4% | C-checks, D-checks, structural composite inspections |
| Digital Systems & Connectivity | US$27 billion | 6.4% | 5.3% (Fastest) | Predictive analytics, satellite Wi-Fi, sensor monitoring |
| Cabin Modifications & Refurbishment | US$21 billion | 5.0% | ~3.5% | Premium economy retrofits, cabin densification |
| Aviation Training & Certification | US$17 billion | 4.0% | ~4.1% | Type ratings, simulator sessions, technician credentials |
| Total Global Services Market | US$422 billion | 100.0% | 3.8% | Comprehensive global fleet operational support |
| Personnel Category | Cumulative 2045 Requirement | Percentage of New Workforce | Core Operational Responsibility |
|---|---|---|---|
| Cabin Crew | 1,050,000 | 43.0% | Cabin safety compliance, medical response, service delivery |
| Maintenance Technicians | 730,000 | 29.9% | Licensed airframe, powerplant, and avionics sign-offs |
| Commercial Airline Pilots | 660,000 | 27.0% | Multi-engine type ratings, captaincy progression, command |
| Total Qualified Workforce | 2,440,000 | 100.0% | Sustaining 45,550 commercial aircraft in revenue flight |
Source: Compiled from Airbus Global Services Forecast 2026–2045 official technical disclosures and fleet database filings.
The Fleet Replacement Equation and Emerging Market Concentration
The anticipated fleet expansion from today’s inventory to 45,550 operational aircraft by 2045 requires 42,060 gross deliveries. Significantly for fleet planners, 19,820 of these new aircraft—representing 47.1% of all production slots—will serve as direct replacements for aging aircraft scheduled for retirement, rather than net fleet additions. This high replacement velocity is dictated by stricter fuel-burn thresholds, noise restrictions, and the escalating maintenance cost of aging aluminum airframes.
Geographically, commercial aviation demand is tilting decisively toward Asia. While North America and Europe (including the Commonwealth of Independent States) maintain massive legacy fleets requiring constant component replenishment, passenger traffic growth of 3.9% annually is overwhelmingly powered by India, Vietnam, Indonesia, and Malaysia. In these developing markets, low-cost carriers are connecting secondary and tertiary city pairs, generating distributed maintenance requirements away from traditional capital city hubs.
Expert Analysis: MRO Capacity Bottlenecks, Pilot Scarcity, and Airfare Inflation
The doubling of the aviation services market exposes a systemic bottleneck that will dictate airline reliability and ticket pricing for decades. While aerospace manufacturers have successfully scaled airframe production, global MRO hangar availability, certified engine overhaul slots, and technician training pipelines have lagged severely behind.
According to data compiled by the International Air Transport Association (IATA) and safety standards set by the International Civil Aviation Organization (ICAO), airlines are already experiencing extended aircraft-on-ground (AOG) events due to microchip shortages and limited engine shop capacity. For travelers booking this route, the direct consequence is chronic schedule fragility, higher rates of last-minute flight cancellations during operational disruptions, and fewer spare aircraft available in airline networks to recover delayed itineraries.
Additionally, training 2.44 million crew members and technicians requires immense capital expenditure. The pricing pressure this creates means airlines will absorb surging labor compensation packages and elevated MRO shop-visit invoices, which will inevitably be transferred to retail passengers via higher base fares and unbundled ancillary fees.
To prevent cascading cost escalations, carriers are investing aggressively in the US$27 billion digital analytics sector. Predictive maintenance systems using onboard engine telemetry can identify hairline stress fractures, exhaust gas temperature spikes, and bearing wear hours before physical sensor failures trigger emergency diversions. By converting unscheduled mechanical failures into planned overnight hangar inspections, airlines hope to protect high aircraft utilization rates in an era of constrained labor.
Key Takeaways
- Market Valuation Doubling: The global commercial aviation services market is projected to expand 101.9% from US$209 billion in 2026 to US$422 billion annually by 2045.
- Massive Human Capital Demand: The industry requires 2.44 million new aviation professionals by 2045, including 1.05 million cabin crew, 730,000 technicians, and 660,000 pilots.
- Fleet Scale and Replacement Dynamics: The global operational fleet will reach 45,550 aircraft; of 42,060 expected deliveries, 47.1% (19,820 airframes) will replace retired aircraft.
- Maintenance Dominates Expenditure: Engine overhauls, component repairs, and airframe inspections will account for US$357 billion, or 84.6% of total services spending by 2045.
- Digital Systems Lead Growth: Telemetry and predictive maintenance software will grow at 5.3% annually to reach US$27 billion, tripling in size to combat technician shortages.
FAQ: Airbus Global Services Forecast 2045
What is the projected value of the aviation services market by 2045?
Airbus projects that the global commercial aviation services market will reach US$422 billion annually by 2045, more than doubling from its US$209 billion valuation in 2026.
How many new pilots and technicians will the aviation industry require?
Between 2026 and 2045, the industry will require 2.44 million new professionals: 660,000 pilots, 730,000 maintenance technicians, and 1,050,000 cabin crew members.
What percentage of new aircraft deliveries will replace older planes?
Of the 42,060 new aircraft deliveries projected through 2045, 19,820 aircraft—or approximately 47.1%—will directly replace retiring aircraft to improve fuel efficiency.
What is the fastest-growing sector within aviation services?
Digital systems and connected aircraft services represent the fastest-growing category, expanding at 5.3% annually to reach US$27 billion by 2045, driven by predictive maintenance algorithms.
[The future of global flight will not be decided by how many aircraft manufacturers can construct, but by the availability of certified hands capable of keeping them airworthy.]
Related Travel Guides
- Emirates Up-Gauges A380 Operations in Malaysia, Switzerland, and China: Strategic Fleet Allocations Reshape Long-Haul Capacity
- EZY Airlines Links U-Tapao With Hua Hin and Surat Thani: Point-to-Point Regional Aviation Bypasses Bangkok
- Delta Overhauls Business Class Hospitality: Comfort Cuisine, Missoni Amenities, and Transoceanic Service Strategy
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Naina Thakur
Contributor & Travel Specialist
Travel enthusiast and legal writer covering visa regulations, responsible tourism, and cultural journeys across global destinations.
Learn more about our team →