Bali Villa Investment Reality Check: Tourism Economic Shifts and Real Estate Correction in 2026
Bali tourism faces real estate market corrections in 2026 as villa oversupply, statutory PBG compliance, and 6%-9% yields replace 20% ROI hype.
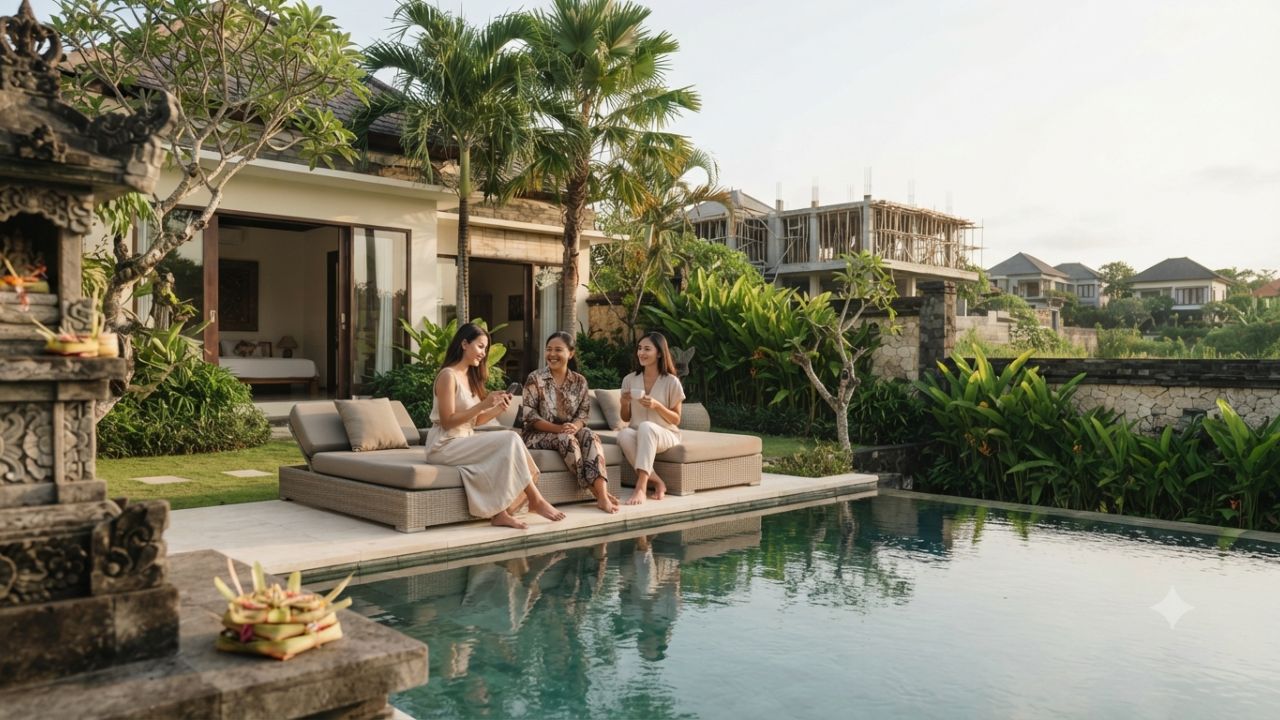
Image generated by AI
Bali's tourism real estate market is undergoing a major economic correction in 2026, as an oversupply of short-term rental villas, aggressive statutory zoning enforcement, and realistic 6% to 9% net yields replace promotional claims of guaranteed 20% returns across major holiday corridors.
Following a massive capital influx between 2022 and 2024, the island experienced an unprecedented construction boom. However, rapid short-term inventory growth drastically outpaced visitor arrivals, triggering intense market competition, declining villa occupancy rates, and operational strain for undercapitalized property managers. Industry assessments backed by the Ministry of Tourism and Creative Economy emphasize that sustainable hospitality development must align with verified visitor demographics rather than speculative marketing hype.
[ BALI TOURISM REAL ESTATE MARKET CORRECTION ARCHITECTURE 2026 ]
  │
  ├── 1. VISITOR VOLUMES      ──► 6.94M (2025 Record) | 3.9M (H1 2026) | Australia (23%)
  ├── 2. OCCUPANCY GAP        ──► Star Hotels (67.29%) vs Standalone Villas (36%-42%)
  ├── 3. REALITY YIELD REVISION──► Marketing ROI Hype (20%) ──► Actual Net Yield (6%-9%)
  ├── 4. STATUTORY ENFORCEMENT──► Mandatory PBG Permit | SLF Certificate | Rp 244B Tax Target
  └── 5. STRUCTURAL SHIFT     ──► Managed Resort Communities Replacing Fragmented Villas
Deconstructing Bali's 2026 Villa Oversupply and Financial Correction
Aggressive off-plan marketing campaigns frequently promise annual returns of 15% to 20%. In operational reality, true sustainable rental yields cluster between 6% and 9% for self-managed units, while professionally managed portfolios achieve 10% to 15% net cash flow after accounting for management commissions, tax deductions, and maintenance reserves.
Official hospitality reports published by Statistics Indonesia (BPS) reveal a stark performance divergence between traditional hotel infrastructure and standalone residential holiday rentals:
- Star-Rated Hotels: Recorded an average room occupancy rate of 67.29% in July 2026, with five-star luxury resorts reaching 74.45%.
- Standalone Vacation Villas: Experienced average annual occupancy rates of just 36% to 42%, reflecting severe inventory saturation in high-density areas like Canggu and Seminyak.
| Micro-Market / Category | Land Valuation / Price Range | Baseline Occupancy Rate | Real Net Rental Yield | Operational Risk Profile |
|---|---|---|---|---|
| Canggu Commercial Core | $345,000 per are (~100 sqm) | 36% - 42% (Villas) | 6% - 9% (Self-managed) | High oversupply & intense pricing competition |
| Uluwatu Growth Corridor | 40% cheaper land than Canggu | 40% - 45% (Villas) | 10% - 15% (Managed) | Emerging infrastructure; strong capital growth |
| 5-Star Luxury Hotels | Premium luxury inventory | 74.45% (BPS July 2026) | Institutional hotel yield | Professional management & global brand distribution |
| Star-Rated Hotels (Overall) | Island-wide hotel standard | 67.29% (BPS July 2026) | Stable hotel yield | Fully compliant statutory permits & safety standards |
| Off-Plan Villa Projects | $300,000 - $600,000 leasehold | 0% (38% Stalled Projects) | Negative / Contested | 18+ month delays due to developer undercapitalization |
Real Estate Performance Metrics Across Bali Micro-Markets
Typical investor-grade leasehold villas require capital outlays between $300,000 and $600,000, while the broader island median ranges from $256,000 to $299,000. However, significant pricing disparities define localized micro-markets:
- Canggu & Seminyak: Prime commercial plots command premium prices up to $345,000 per are (100 sqm), leading to high acquisition costs and compressed yields.
- Uluwatu & Bukit Peninsula: Emerging growth zones offer land valuations roughly 40% lower than Canggu while commanding comparable high-end nightly rates, attracting capital for long-term appreciation (historically averaging 7% to 15% annually in prime zones).
Demographics and Visitor Volumes Shaping Island Hospitality
Understanding visitor source markets is vital for structuring villa marketing. According to official tourist board data from Wonderful Indonesia, Bali recorded a record 6.94 million foreign visitor arrivals in 2025 (up 9.7% YoY). In the first seven months of 2026, international arrivals reached 3.9 million.
Australia remains Bali’s dominant feeder market, representing nearly 23% of total foreign arrivals with over 982,000 visitors through July 2026. Secondary major markets include India, China, the UK, and France. Properties tailored to specific demographic profiles—such as long-stay digital nomads, surf enthusiasts, or luxury family retreats—consistently maintain higher occupancy than generic holiday rentals.
Statutory Compliance: PBG Permits, SLF Certificates, and Tourism Taxes
In response to illegal construction and environmental degradation, municipal authorities have intensified enforcement of statutory building codes and zoning laws.
Operating a legal short-term rental now requires strict compliance:
- PBG Building Permit (Persetujuan Bangunan Gedung): Mandatory municipal construction clearance verifying structural compliance.
- SLF Certificate (Sertifikat Laik Fungsi): Functionality certificate certifying operational safety before accepting commercial guests.
- Green Zone Restrictions: Properties built within restricted agricultural or green-belt zones face immediate operational shutdowns, heavy fines, and legal action.
- Tourism Tax Collection: Regional tourist tax collections reached Rp 244 billion by August 2026, reflecting the provincial government's commitment to formalizing the holiday accommodation sector.
Star-Rated Hotels vs Standalone Villas: The Occupancy Gap
The divergence between hotel performance and private villas highlights the operational hazards of relying on off-plan promotional projections. While five-star hotels maintain strong occupancy above 74% through global distribution systems, standalone villas face high vacancy during shoulder seasons.
Furthermore, construction outlays averaging $1,000 to $1,800 per square meter, combined with recurring staff salaries, platform commissions (15%-25% of gross revenue), and high tropical humidity maintenance, significantly diminish net cash flow if sinking funds are not established.
Stalled Off-Plan Projects and Developer Undercapitalization Risks
Market tracking indicates that approximately 38% of off-plan villa developments in Bali have suffered severe construction delays or complete halts lasting 18 months or longer due to developer undercapitalization.
Retail buyers who paid large upfront deposits face legal battles and asset illiquidity. As a result, institutional capital is shifting toward turnkey, completed properties or master-planned resort communities featuring centralized amenities, professional concierge teams, and institutional asset management.
Key Market & Financial Highlights
- 2025 Arrival Record: 6.94 million foreign visitors (up 9.7% year-on-year).
- 2026 H1 Visitor Arrival Volume: 3.9 million international arrivals through July 2026.
- Top Source Market: Australia supplies 23% of total arrivals (>982,000 visitors).
- Hotel vs Villa Occupancy: 67.29% for star hotels (74.45% for 5-star) vs 36%-42% for standalone villas.
- Realistic Net Rental Yields: Real yields cluster at 6%-9% (self-managed) and 10%-15% (professionally managed).
- Stalled Off-Plan Rate: 38% of off-plan villa projects face 18+ month delays due to undercapitalization.
Consumer & Investor Travel Impact: What Holidaymakers Need to Know
For travelers and property buyers navigating Bali in 2026:
- Verify Villa Registration: Guests should ensure vacation rentals possess valid PBG permits and municipal operating licenses to avoid booking cancellations caused by zoning crackdowns.
- Expect Inconsistent Service in Unmanaged Rentals: Standalone villas suffering from financial stress may cut back on maintenance, while managed resort communities deliver reliable hospitality standards.
- Prioritize Completed Turnkey Properties: Investors seeking property exposure should avoid unverified off-plan schemes and opt for completed, legally compliant resort assets.
Frequently Asked Questions About Bali Tourism and Villa Investment
What is the average occupancy rate for Bali vacation villas in 2026?
While star-rated hotels average 67.29% occupancy (74.45% for 5-star resorts), standalone private villas average 36% to 42% annual occupancy due to supply overcapacity.
What are the realistic net rental yields for Bali real estate in 2026?
Actual net rental yields cluster between 6% and 9% for self-managed properties and 10% to 15% for professionally managed portfolios, compared to advertised 20% marketing claims.
What legal permits are required to operate a holiday rental in Bali?
Operating a legal short-term rental requires a valid PBG building permit (Persetujuan Bangunan Gedung), an SLF certificate of functionality (Sertifikat Laik Fungsi), and location within a legal commercial tourism zone.
Which country is the largest source of tourists to Bali in 2026?
Australia remains Bali's largest source market, contributing nearly 23% of total international arrivals with over 982,000 visitors recorded through July 2026.
Related Travel Guides
Indonesia, Malaysia, Vietnam, and Thailand Tourism Dominance Guide 2026
North Sulawesi Tourism & Hotel Investment Guide 2026
The 10 Best Luxury Villas and Resort Stays in Bali, According To Reddit
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Kunal K Choudhary
Co-Founder & Contributor
A passionate traveller and tech enthusiast. Kunal contributes to the vision and growth of Nomad Lawyer, bringing fresh perspectives and driving the community forward.
Learn more about our team →