African Aviation Adds 26.6 Million Scheduled Seats: Ethiopian, Royal Air Maroc, and Regional Fleets Expand
Scheduled airline capacity across Africa reached 26.6 million seats in October 2026 as Ethiopian Airlines, Royal Air Maroc, and RwandAir accelerate route expansion.
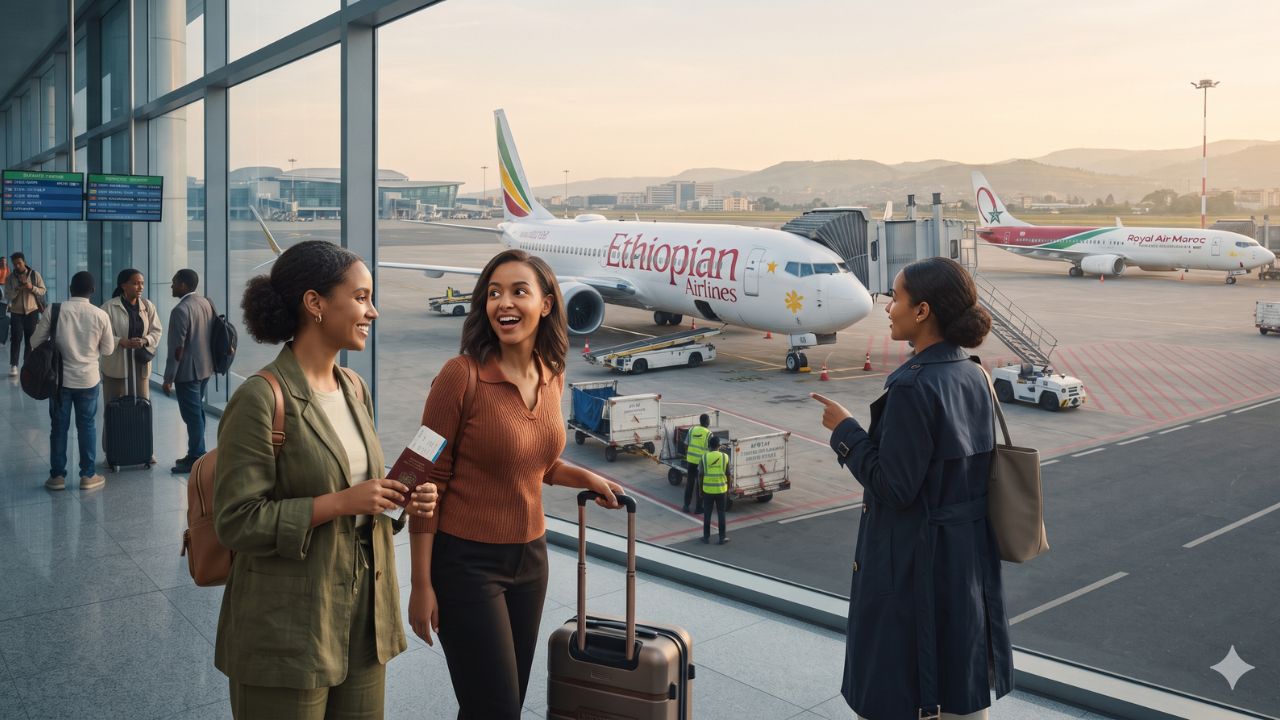
Image generated by AI
Propelled by an 8.8% year-on-year capacity surge that lifted total scheduled airline capacity across the continent to 26.6 million seats in October 2026, Africa’s leading carriers are dismantling historical routing dependencies on European and Gulf transfer hubs. Detailed operational tracking published by the Official Airline Guide (OAG) confirms that domestic seat availability jumped by 11.9% while international scheduled capacity rose by 7.9%. Led by double-digit network expansions from Royal Air Maroc and Ethiopian Airlines, alongside strategic fleet modernization at RwandAir and Airlink, African carriers are re-engineering trans-continental corridors to capture surging intra-regional corporate travel and overseas tourism flows.
Network Transformation: Point-to-Point Regional Corridors and Fleet Modernization
For decades, air travel within Africa was constrained by fragmented bilateral agreements and limited hub-and-spoke infrastructure. Travelers journeying between neighboring economic zones frequently faced circuitous multi-day itineraries transiting through Paris Charles de Gaulle, London Heathrow, or Dubai. The current wave of network development directly targets these historic connectivity gaps. Data compiled by the African Airlines Association (AFRAA) indicates that intra-African seat availability expanded by 10.5% in August 2026 compared to the same period in 2025, demonstrating an aggressive industry pivot toward direct regional routing.
At the forefront of this structural transformation, Ethiopian Airlines continues leveraging its primary hub at Addis Ababa Bole International Airport (ADD) to connect underserved secondary industrial cities with global trade lanes. Between October and December 2026, the carrier is inaugurating three-times-weekly scheduled flights to Nacala, Mozambique (commencing October 27), restoring daily wide-body flights to Durban, South Africa, and adding a direct service to Port Harcourt, Nigeria. These routes bypass congested coastal capitals, linking resource-rich secondary hubs directly into Ethiopian’s intercontinental trans-Pacific and European network.
Concurrently, Royal Air Maroc (RAM) has emerged as one of the fastest-expanding network carriers in the global airline industry. During the summer 2026 operating schedule, the Moroccan flag carrier deployed approximately 8.2 million seats—a 23% increase over summer 2025—operating 67 aircraft across 86 international destinations. OAG capacity metrics confirm RAM's scheduled seat volume for October 2026 expanded by 20.6% year-on-year. Anchored by the June 2026 debut of direct Casablanca (CMN) to Los Angeles (LAX) long-haul flights, RAM is positioning Casablanca as a premier transatlantic gateway linking North America directly to Western and Central Africa.
Continental Fleet Expansion and Bilateral Capacity Performance
The surge in African aviation capacity is distributed unevenly across regional markets, reflecting varied national economic growth trajectories and airline capital health.
The table below outlines the core fleet additions, new route developments, codeshare agreements, and regional capacity growth metrics across major African airline operators in late 2026.
| Carrier & National Base | Fleet Additions & Aircraft Types | New Routes & Service Resumptions | Codeshare & Commercial Alliances | Regional Seat Growth Performance |
|---|---|---|---|---|
| Ethiopian Airlines (Ethiopia) | Boeing 787 / Airbus A350 fleet | Nacala (Oct 27), Port Harcourt, Durban daily (Dec) | Star Alliance global network coordination | Core East African hub volume driver |
| Royal Air Maroc (Morocco) | 67 aircraft active fleet; 8.2M summer seats | Casablanca–Los Angeles (LAX) launched June 2026 | oneworld alliance feeder coordination | +20.6% YoY scheduled seats in Oct 2026 |
| RwandAir (Rwanda) | Airbus A330-200 delivered Aug 2026 | Kigali long-haul expansion into Europe/Mideast | EgyptAir codeshare (Cairo, Rome, Amman) | Strategic Central African transit hub |
| Airlink (South Africa) | Embraer E195-E2 next-gen regional jets | Johannesburg–Zanzibar; Cape Town–Mauritius | Independent interline feeder partnerships | Dominant Southern African regional carrier |
| TAAG Angola (Angola) | 5 aircraft returned to service | Luanda–Dakar–Praia route launching Oct 31, 2026 | Network grew 30% (from 10 to 13 African destinations) | Lusophone Atlantic corridor expansion |
| Kenya Airways (Kenya) | Restored Boeing 787-8 & 777-300ER metal | Capacity down 9% in H1 2026 during fleet overhaul | CemAir codeshare (10 South African domestic cities) | Operational recovery and partner pooling |
| South African Airways (South Africa) | Narrow-body domestic & regional fleet | Core Johannesburg regional trunk routes | Expanded reciprocal Emirates codeshare (9 routes) | +0.8% national capacity growth in Oct 2026 |
| Air Tanzania (Tanzania) | Boeing 787 Dreamliner fleet | Dar es Salaam–Moscow–Zanzibar service launched | Direct Russian leisure tourism access | Long-haul tourist charter conversion |
| Air Algérie (Algeria) | Mixed Airbus/Boeing fleet | Manchester & Libreville (2x weekly launched June) | North-to-Sub-Saharan African transit | Western Mediterranean hub diversification |
| Air Sénégal (Senegal) | Regional Airbus A220/ATR fleet | Dakar–Bamako–Ouagadougou route restored July 2026 | Restored intra-Sahelian connectivity | West African regional corridor stabilization |
| EgyptAir (Egypt) | Long-haul wide-body fleet with Wi-Fi | Direct Cairo–Los Angeles route launched May 2026 | RwandAir reciprocal codeshare partnership | +9.6% national capacity growth in Oct 2026 |
National market divergence is pronounced. In Nigeria, total scheduled seat capacity exploded by 44.5% year-on-year in October 2026, driven by a 54.6% surge in domestic capacity reaching 1.03 million seats. Central and Western Africa recorded collective capacity growth of 19.6%, while Egypt (+9.6%) and Morocco (+11%) sustained strong growth. Conversely, South Africa logged a modest 0.8% capacity expansion, reflecting cautious domestic airline consolidation.
Expert Analysis: Fuel Premiums, Bilateral Codeshares, and Itinerary Economics
For travelers booking this route, the direct consequence of expanding intra-African airline capacity is a marked reduction in overall transit duration paired with increased multi-carrier itinerary choices. By utilizing codeshare partnerships such as the Kenya Airways–CemAir alliance—which links 15 Kenya Airways destinations to 10 South African domestic cities and four regional destinations—passengers can ticket complex multi-stop journeys across East and Southern Africa under a single booking reference, with baggage checked straight through to final destinations.
The pricing pressure this creates means airfares across historical trunk routes face competitive deflation, although elevated operating costs establish a firm fare floor. A primary commercial hurdle confronting African carriers is disproportionate fuel overhead. Official AFRAA benchmarks document that for the week ending August 21, 2026, the average price of jet fuel in Africa stood at $169.01 per barrel, significantly exceeding the global average of $163.87 per barrel. This structural fuel price premium—driven by regional refinery deficits, high import logistics costs, and local pipeline tariffs—means African airlines operate with thinner operating margins than their Middle Eastern or European competitors, preventing drastic low-cost fare reductions.
Furthermore, aircraft maintenance turnaround times and supply-chain bottlenecks continue testing fleet availability. While Kenya Airways successfully returned flagship Boeing 787-8 Dreamliners and Boeing 777-300ERs to active flight lines, its 9% capacity reduction in the first half of 2026 underscores that restoring grounded aircraft requires substantial capital and lengthy maintenance checks. Carriers that overcome these fleet constraints, such as RwandAir with its newly delivered Airbus A330-200 and Airlink with its fuel-efficient Embraer E195-E2s, capture a competitive advantage by deploying high-efficiency modern cabins on key leisure corridors like Cape Town to Mauritius and Johannesburg to Zanzibar.
Long-term connectivity gains will ultimately depend on regulatory liberalization under the Single African Air Transport Market (SAATM). As airlines bypass restrictive bilateral air service agreements through interline partnerships—such as EgyptAir and RwandAir expanding coordinated booking channels into Rome, Cairo, and Amman—international travelers gain seamless access to emerging African commercial centers without relying on non-African carriers.
Key Takeaways
- 26.6 Million Scheduled Seats: Total airline seat capacity in Africa reached 26.6 million in October 2026, marking an 8.8% year-on-year growth according to OAG data.
- Intra-African Connectivity Surges 10.5%: AFRAA reported double-digit growth in direct flights between African nations, reducing historical reliance on European transit hubs.
- Nigerian Aviation Market Booms: Scheduled seat capacity in Nigeria surged 44.5% in October, with domestic seats increasing 54.6% to reach 1.03 million seats.
- High-Growth Carrier Strategies: Royal Air Maroc expanded capacity by 20.6% in October with 86 international routes, while Ethiopian Airlines added routes to Nacala, Port Harcourt, and Durban.
- Persistent Jet Fuel Surcharge Burden: African airlines face average jet fuel costs of $169.01 per barrel compared to the $163.87 global benchmark, keeping operating expenses high.
FAQ: African Airline Route Expansion 2026
Which African airlines are adding new direct international routes?
Ethiopian Airlines is adding flights to Nacala, Port Harcourt, and Durban; Royal Air Maroc launched direct Casablanca–Los Angeles flights; Air Tanzania introduced Dar es Salaam–Moscow–Zanzibar; and Air Algérie launched Manchester and Libreville routes.
How does the Kenya Airways and CemAir partnership benefit passengers?
The agreement allows Kenya Airways passengers to connect seamlessly to 10 domestic and 4 regional destinations in South Africa served by CemAir, while CemAir travelers gain access to 15 destinations on Kenya Airways' African network.
Why are flight tickets within Africa often more expensive than in Europe?
Intra-African flights carry higher operating costs due to regional jet fuel price premiums ($169.01/barrel in Africa vs. $163.87 globally), airport infrastructure taxes, and limited low-cost carrier penetration across international borders.
What aircraft are being deployed on new regional leisure routes?
South African carrier Airlink is deploying modern Embraer E195-E2 aircraft on Johannesburg–Zanzibar and Cape Town–Mauritius routes, while RwandAir expanded its long-haul fleet with an Airbus A330-200.
International travelers and regional business professionals should take advantage of newly launched direct intra-African routes to bypass long-haul layovers and reduce transit times.
Related Travel Guides
The 10 Best Connecting Routes Across Africa, According To Reddit
Disclaimer
This article is for informational and educational purposes only. It does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, travel policies, regulations, and conditions change rapidly. Always verify information with official sources before making travel decisions. Nomad Lawyer makes no representations about the accuracy, reliability, completeness, or suitability of the information provided. Readers should consult qualified professionals for advice specific to their circumstances. The views expressed in this article are those of the author and do not necessarily reflect the views of Nomad Lawyer.
Kunal K Choudhary
Co-Founder & Contributor
A passionate traveller and tech enthusiast. Kunal contributes to the vision and growth of Nomad Lawyer, bringing fresh perspectives and driving the community forward.
Learn more about our team →